India's data centres on track for 2 GW by year-end as 200 MW set for H2 2026
Synopsis
India is closing in on a 2 GW data centre milestone by year-end 2026 — a scale that has earned it a seat alongside Japan and Australia in Asia Pacific's top tier. With $173 billion in cumulative commitments, AI-linked demand crossing 15 per cent, and domestic investors and developers now leading the market, this is no longer a growth story. It is a maturity story.
Key Takeaways
India added approximately 130 MW of data centre capacity in H1 2026 and over 200 MW more is expected in H2 2026 , targeting 2 GW total by year-end.
Mumbai accounted for 94 per cent of new supply in H1 2026, cementing its role as the national hub.
Cumulative investment commitments since 2021 have reached approximately $173 billion ; $38 billion was committed in H1 2026 alone.
Over 15 per cent of cumulative commitments are linked to artificial intelligence -driven demand.
India was upgraded to Asia Pacific's 'Leading Data Centre Markets' category in 2026, joining Japan , Australia , and Mainland China .
Domestic investors hold 38 per cent of cumulative capital deployed; domestic developers supplied 48 per cent of new H1 capacity, outpacing US and European players.
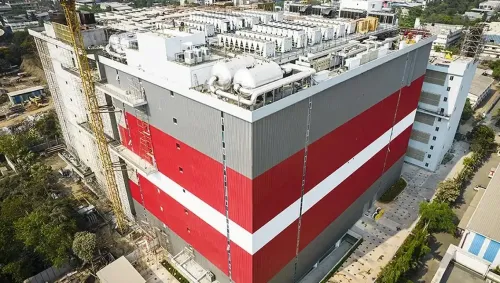
India is on course to cross 2 GW of operational data centre capacity by end-2026, after adding approximately 130 MW of new supply in the first half of the year and with over 200 MW more expected in the second half, according to a report by CBRE South Asia Pvt. Ltd. The findings position India among Asia Pacific's elite data centre markets, a ranking few economies in the region have achieved at this pace.
Mumbai Dominates New Supply
Mumbai accounted for 94 per cent of all new data centre capacity added in H1 2026, reinforcing its status as the country's undisputed primary hub. The city's concentration of hyperscale operators, submarine cable landing stations, and power infrastructure continues to make it the default gateway for both domestic and international investment in the sector.
Investment Commitments Surge Past $173 Billion
The sector attracted nearly $38 billion in fresh investment commitments during H1 2026 alone, bringing cumulative commitments since 2021 to approximately $173 billion. Of that cumulative figure, hyperscale and colocation segments accounted for close to 62 per cent. Notably, over 15 per cent of cumulative commitments were linked to artificial intelligence-driven demand — a share expected to grow as enterprise AI adoption deepens across sectors.
'India's data centre sector continues to scale at a pace few markets in the region can match,' said Anshuman Magazine, Chairman and CEO, India, South-East Asia, Middle East and Africa, CBRE. 'India's cumulative investment commitments of over $170 billion, Mumbai's continued leadership, and a rising share of AI-linked capital all point to a market that is maturing even as it expands. This also reinforces India's position within Asia Pacific, where data centres remain among investors' most preferred asset classes,' he added.
India Joins Asia Pacific's Top-Tier Markets
The CBRE report upgraded India from a 'High Growth Market' to the 'Leading Data Centre Markets' category within Asia Pacific in 2026, placing it alongside Japan, Australia, and Mainland China. Data centres ranked as the fourth most preferred asset class in CBRE's 2026 Asia Pacific Investor Intentions Survey, signalling sustained institutional appetite.
Domestic Investors and Developers Lead the Charge
The sector's facility quality is also rising sharply. The share of Tier IV data centres — the highest resilience classification — climbed to 43 per cent of overall supply in H1 2026, up from just 21 per cent in 2024. Multi-city portfolios accounted for more than 85 per cent of commitments in H1 2026, reflecting a shift from single-market bets to national-scale strategies.
Domestic investors retained the largest share of cumulative capital deployed since 2021, at 38 per cent, ahead of investors from the United States at 27 per cent. On the supply side, domestic developers delivered 48 per cent of new capacity in H1 2026, outpacing both American and European players — a reversal of the early-cycle dynamic when foreign hyperscalers dominated new builds.
With the second half of 2026 expected to bring even higher additions, India's digital infrastructure buildout is entering a phase where scale, quality, and sovereign capital are converging simultaneously.
Point of View
The power, water, and grid implications for cities like Mumbai become a policy constraint, not just a commercial opportunity. The dominance of domestic investors at 38 per cent also deserves scrutiny — it suggests Indian capital is backing the sector with conviction, but concentration risk in a single city (Mumbai at 94 per cent of H1 supply) remains a structural vulnerability that neither the government nor the industry has visibly addressed.
NationPress
6 Oct 2026
Frequently Asked Questions
What is India's data centre capacity target for 2026?
India is on track to reach 2 GW of operational data centre capacity by the end of 2026, according to a CBRE South Asia report. The country added approximately 130 MW in H1 2026 and is expected to add over 200 MW more in the second half of the year.
Why is Mumbai so dominant in India's data centre market?
Mumbai accounted for 94 per cent of all new data centre supply added in H1 2026, driven by its concentration of hyperscale operators, submarine cable infrastructure, and established power networks. Its position as the country's financial and connectivity hub makes it the preferred location for large-scale deployments.
How much has been invested in India's data centre sector?
Cumulative investment commitments since 2021 have reached approximately $173 billion, with nearly $38 billion committed in H1 2026 alone. Hyperscale and colocation segments account for close to 62 per cent of that cumulative figure.
What role is AI playing in India's data centre growth?
Over 15 per cent of cumulative investment commitments since 2021 are linked to artificial intelligence-driven demand, according to CBRE. As enterprise AI adoption expands across sectors, this share is expected to grow further.
How does India now rank among Asia Pacific data centre markets?
India was upgraded to the 'Leading Data Centre Markets' category within Asia Pacific in 2026, joining Japan, Australia, and Mainland China. Data centres also ranked as the fourth most preferred asset class in CBRE's 2026 Asia Pacific Investor Intentions Survey.