India real estate enters NOI-led value phase, JLL report says
Synopsis
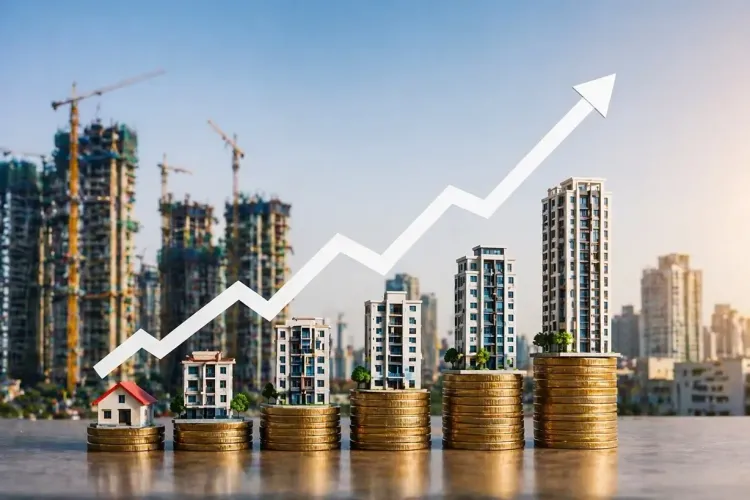
India's decade-long commercial real estate boom — fuelled by sharp cap rate compression — is giving way to a harder, more disciplined era of income-driven returns. With $78 billion in institutional capital already deployed and 600 million sq ft in the pipeline, JLL says the next winners won't be early movers but smart operators who pick the right assets and squeeze more out of them.
Key Takeaways
India real estate has entered a NOI-driven value creation phase , moving away from cap rate compression as the primary return engine, according to a JLL report dated 2 November 2026 .
The sector has attracted approximately $78 billion in institutional capital since 2014 .
Cap rates have compressed by 270 bps (office), 320 bps (retail), and 250 bps (warehousing) between 2016 and Q3 2026 .
A supply pipeline of over 600 million sq. ft spans office, warehousing, and retail, with 200 million sq. ft of non-premium office stock available for repositioning.
A 40 million sq. ft premium office pipeline through 2030 — 70% premium — is expected to reshape the institutional landscape.
Double-digit returns remain achievable for investors holding high-quality office assets over a five-year horizon, JLL says.
India's real estate market has entered a new phase of value creation in which investment returns will be driven increasingly by net operating income (NOI) growth and strategic asset selection, according to a report released on Monday, 2 November 2026 by property consultancy JLL. The shift marks a decisive turn away from the decade-long era of capitalisation rate compression that defined the sector's earlier institutional maturation.
The New Return Calculus
According to JLL, investors can still generate double-digit returns by holding high-quality office properties over a typical five-year investment period — but the engine has changed. Where returns once rode on falling cap rates, they must now be earned through income growth and disciplined asset selection. The report notes that the era of market-wide re-rating is effectively over, given the trajectory of interest rates globally.
Lata Pillai, Senior Managing Director and Head of Capital Markets, India, at JLL, put it plainly: 'India's real estate market has reached a pivotal moment, moving beyond an era of market-wide re-rating to one focused on sophisticated, long-term value creation. The past decade was defined by a significant re-rating, with capitalisation rates compressing sharply across all key commercial sectors.'
Pillai added: 'The next phase will be about building value, driven by income growth rather than cap rate movement. The era of returns driven by market-wide cap rate compression is behind us, as the scope for further compression is limited given the way interest rates are moving.'
A Decade of Institutional Maturity
India's real estate sector has attracted approximately $78 billion in institutional capital since 2014, underscoring its transition into a mainstream investment destination. One of the clearest signs of that maturity, the report argues, is the notable compression in capitalisation rates already achieved: office cap rates have tightened by 270 basis points, retail by 320 basis points, and warehousing by 250 basis points between 2016 and Q3 2026. That compression, having done its work, leaves limited room for further gains — making income quality the next differentiator.
Supply Pipeline and Capital Deployment Pathways
The JLL report identifies a substantial pipeline that offers structured opportunities across the risk spectrum. Over 600 million square feet of new supply across office, warehousing, and retail sectors is in the pipeline, alongside 200 million square feet of non-premium office stock ready for repositioning. This range — from core institutional assets to value-add repositioning and opportunistic development — gives investors clearly defined entry points at varying risk tolerances.
Notably, a 40 million sq. ft office supply pipeline running through 2030, of which 70% is classified as premium, is expected to fundamentally reshape the landscape and provide long-term support for institutional portfolio growth.
What This Means for Investors
This comes amid a broader global recalibration of real estate valuations, as higher-for-longer interest rate environments in developed markets have compressed returns in those geographies and redirected capital flows toward high-growth emerging markets like India. The shift to NOI-driven returns demands more active asset management, deeper tenant relationships, and a focus on operational efficiency — capabilities that distinguish institutional-grade operators from passive capital allocators.
With the supply pipeline defined and cap rate compression largely exhausted, the next chapter of India's commercial real estate cycle will reward investors who select the right assets and manage them well — not simply those who arrived early.
Point of View
Weaker operators who rode the tide get exposed. The pivot to NOI-driven returns will pressure mid-tier asset owners who lack active management capabilities. Meanwhile, the 200 million sq. ft repositioning opportunity is the real story hiding in the numbers — value-add plays in non-premium office stock could define the next wave of outperformance. What the report doesn't address is the risk concentration: with 70% of the upcoming premium pipeline arriving by 2030, a demand slowdown in that window could test valuations that are no longer propped by rate tailwinds.
NationPress
2 Nov 2026
Frequently Asked Questions
What is the new value creation phase in India's real estate market?
It refers to a shift in how investment returns are generated — from capitalisation rate compression to net operating income (NOI) growth and strategic asset selection, as identified in a JLL report released on 2 November 2026. The era of market-wide re-rating is considered over, with income quality now the primary driver of returns.
How much institutional capital has India's real estate attracted since 2014?
India's real estate sector has attracted approximately $78 billion in institutional capital since 2014, according to the JLL report. This inflow reflects the sector's transition into an institutional-grade investment destination.
What has happened to capitalisation rates in India's real estate market?
Office cap rates have tightened by 270 basis points, retail by 320 basis points, and warehousing by 250 basis points between 2016 and Q3 2026, according to JLL. The significant compression leaves limited room for further gains, which is why income growth is now the key return driver.
What is the real estate supply pipeline in India?
Over 600 million square feet of new supply across office, warehousing, and retail is in the pipeline, alongside 200 million square feet of non-premium office stock available for repositioning. An additional 40 million sq. ft of premium office supply is expected to arrive by 2030, 70% of which is classified as premium grade.
Can investors still earn double-digit returns in India's real estate market?
Yes, according to JLL, investors can still earn double-digit returns by holding high-quality office properties over a typical five-year investment period. However, these returns must now be earned through NOI growth and disciplined asset management rather than passive cap rate compression.