Kaynes Technology shares slide 16% in 2 days after Jefferies cuts target price 19%
Synopsis
Kaynes Technology's stock has shed roughly 16% over two sessions after its Q2 FY27 net profit collapsed to ₹39.8 crore from ₹115.7 crore a year ago, and Jefferies slashed its target price by 19%, cutting its long-term earnings growth forecast from 40% to 31% CAGR. The selloff exposes the margin vulnerability lurking beneath the Indian EMS sector's headline growth story.
Key Takeaways
Kaynes Technology shares fell a combined ~16% over two sessions, trading at ₹2,899 on 17 November 2026 .
Consolidated net profit for Q2 FY27 collapsed to ₹39.8 crore from ₹115.7 crore in the year-ago quarter.
EBITDA margin narrowed sharply from 12.7% to 4.2% , hurt by rising input costs, higher depreciation, and elevated interest expenses.
Jefferies cut its target price by 19% and trimmed its FY27–FY29 earnings estimates, lowering expected CAGR from ~40% to ~31% .
Revenue still grew 4.4% YoY to ₹952.5 crore , indicating demand held up even as margins deteriorated.
Shares of Kaynes Technology remained under sustained selling pressure for the second straight session on Tuesday, 17 November 2026, declining nearly 3 per cent on the National Stock Exchange (NSE) after a sharp 13 per cent crash in the previous session. The two-day rout, totalling roughly 16 per cent, followed a weaker-than-expected Q2 FY27 earnings print and a subsequent target-price cut by global brokerage Jefferies.
How the Stock Traded
During noon trade, Kaynes Technology shares were changing hands at ₹2,899 apiece on the NSE, down 2.72 per cent from the previous close. At its intra-day low, the stock touched ₹2,865 — a decline of as much as 3.8 per cent — even as the broader benchmark Nifty50 gained 0.59 per cent in the same session, underscoring the company-specific nature of the pressure.
What the Q2 FY27 Numbers Showed
The electronics manufacturing services (EMS) company reported a consolidated net profit of ₹39.8 crore for the September quarter (Q2 FY27), a steep fall from ₹115.7 crore in the year-ago period. Revenue, however, edged up 4.4 per cent year-on-year to ₹952.5 crore, compared with ₹912.1 crore in the corresponding quarter of the previous fiscal.
Operating performance deteriorated sharply. EBITDA declined 16.2 per cent to ₹125.6 crore from ₹149.8 crore a year earlier, according to the company's stock exchange filing. More strikingly, the EBITDA margin compressed from 12.7 per cent to just 4.2 per cent — a contraction that alarmed analysts. Higher depreciation, elevated interest expenses, and lower other income together dragged net profit down even as top-line growth remained positive.
What Jefferies Said
Reacting to the results, Jefferies said the quarterly performance fell well short of its estimates. The brokerage highlighted subdued revenue growth of around 4 per cent and margin compression driven by rising input costs as the two key pressure points. In response, it cut its earnings estimates for FY27 through FY29 and reduced its valuation multiple, resulting in a 19 per cent reduction in its target price on the stock.
Jefferies now expects Kaynes Technology to deliver earnings growth at a compound annual growth rate (CAGR) of around 31 per cent between FY26 and FY29, down from an earlier projection of nearly 40 per cent. That downward revision in the long-term growth outlook is a significant rerating signal for a stock that had commanded a premium valuation on high-growth expectations.
Broader Context for EMS Sector
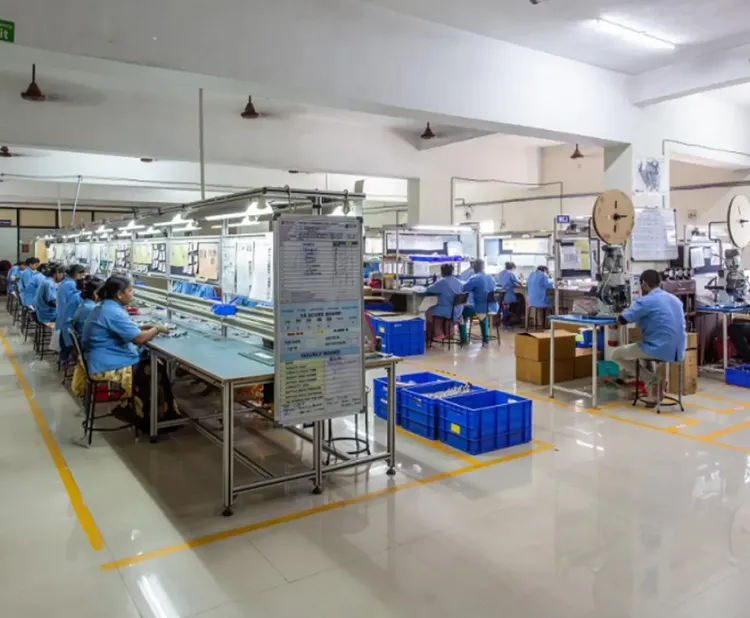
Kaynes Technology is one of a handful of listed Indian EMS players that have benefited from the domestic electronics manufacturing push under government PLI schemes. This comes amid a broader phase of margin normalisation across the sector, as input cost inflation and capex-related depreciation weigh on near-term profitability. Notably, the company's revenue trajectory — still showing year-on-year growth — suggests demand is not collapsing, but execution costs are rising faster than pricing power allows.
How Kaynes Technology manages its cost structure and margin recovery in the second half of FY27 will be closely watched by investors reassessing the EMS sector's near-term earnings visibility.
Point of View
And Jefferies is likely not the only broker sharpening its pencil. The more structural concern is whether Kaynes and its EMS peers can convert top-line government-backed demand into consistent bottom-line delivery as capex loads and input costs intensify. If the margin story does not recover by Q4 FY27, the sector's re-rating risk becomes systemic, not idiosyncratic.
NationPress
17 Nov 2026
Frequently Asked Questions
Why are Kaynes Technology shares falling?
Kaynes Technology shares have fallen roughly 16% over two sessions after the company reported a steep drop in Q2 FY27 net profit to ₹39.8 crore, down from ₹115.7 crore a year ago, with EBITDA margin narrowing sharply to 4.2%. Global brokerage Jefferies followed up by cutting its target price on the stock by 19%, triggering further selling.
What did Jefferies say about Kaynes Technology?
Jefferies said Kaynes Technology's Q2 FY27 performance fell well short of its estimates, citing subdued revenue growth of around 4% and significant margin compression from rising input costs. The brokerage cut its earnings estimates for FY27–FY29 and now projects a CAGR of around 31% for the period, down from a prior forecast of nearly 40%.
What were Kaynes Technology's Q2 FY27 financial results?
Kaynes Technology reported a consolidated net profit of ₹39.8 crore for Q2 FY27, a sharp decline from ₹115.7 crore in the same quarter last year. Revenue rose 4.4% YoY to ₹952.5 crore, but EBITDA fell 16.2% to ₹125.6 crore and EBITDA margin contracted from 12.7% to 4.2%.
What is Kaynes Technology's business?
Kaynes Technology is an electronics manufacturing services (EMS) company listed on Indian exchanges. It manufactures printed circuit board assemblies and electronic systems for sectors including automotive, aerospace, and industrial, and has been a beneficiary of India's domestic electronics manufacturing push.
What should investors watch next for Kaynes Technology?
Investors will focus on whether Kaynes Technology can recover its EBITDA margin in the second half of FY27, particularly as input costs and depreciation from recent capex investments continue to weigh. Any further analyst downgrades or updates to guidance from the management will be key near-term triggers for the stock.