Zimbabwe in talks to adopt India's UPI stack for real-time payments rail
Synopsis
Zimbabwe could become the latest nation to run its payments system on India's UPI stack — and with diaspora remittances at $2.45 billion a year and sub-Saharan Africa paying nearly 8% to send $200, the potential impact is enormous. Negotiations with NPCI International are reportedly set to conclude by 31 October, with Ghana, Uganda, Rwanda, and Mozambique already watching closely.
Key Takeaways
Zimbabwe is in negotiations with NPCI International Payments Ltd (NIPL) to licence UPI technology as a shared domestic real-time payments rail.
Talks could be concluded by 31 October 2026 , according to Reserve Bank of Zimbabwe governor John Mushayavanhu .
Zimbabwe processed 238 million electronic transactions in Q4 2025 , with mobile money making up 87% of volume.
Diaspora inflows into Zimbabwe reached $2.45 billion in 2025 , averaging $6.7 million a day .
Sub-Saharan Africa's average remittance cost was near 8% in 2025, more than double the SDG target of 3% .
Ghana , Uganda , Rwanda , and Mozambique have also signalled interest in partnering with NPCI.
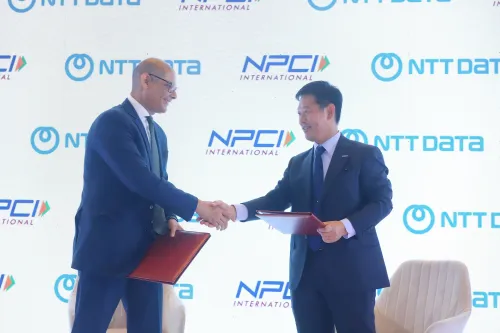
Zimbabwe is in advanced negotiations with NPCI International Payments Ltd (NIPL) — the overseas arm of India's National Payments Corporation of India (NPCI) — to licence the technology underpinning the Unified Payments Interface (UPI) as a shared domestic real-time payments rail, according to a report by India Narrative. Talks could reportedly conclude by 31 October 2026, potentially making Zimbabwe the latest African nation to adopt India's flagship payments infrastructure.
What the UPI Rail Would Do for Zimbabwe
A shared domestic rail built on UPI architecture would allow banks, mobile-money operators, and fintechs to clear transfers in real time on a single public layer — something Zimbabwe currently lacks despite a high volume of digital transactions. Reserve Bank of Zimbabwe governor John Mushayavanhu said the move could cut transaction costs, accelerate transfers, and create an account-to-account alternative to cards for small domestic payments.
Zimbabwe's national payments system processed 238 million electronic transactions in Q4 2025, with mobile money accounting for roughly 87% of that volume and active mobile-financial-services users numbering close to 11 million. The absence of a low-cost common rail means these volumes are being cleared across fragmented, higher-cost channels.
The Remittance Dimension
Governor Mushayavanhu also indicated that cross-border use and remittance links could follow once the domestic rail is established. The stakes are considerable: Zimbabwe's diaspora inflows reached $2.45 billion in 2025, up from $2.15 billion in 2024, averaging roughly $6.7 million a day. Britain and South Africa each contributed a little over a quarter of early-2025 flows, according to the report. These remittances represent household income and a critical source of foreign exchange, ranking second only to mining in economic significance.
The cost dimension adds urgency. The World Bank estimated sub-Saharan Africa's average cost of sending $200 at near 8% in 2025, against a global average of about 6.5% and a Sustainable Development Goal (SDG) target of 3%. Costs on Southern African Development Community (SADC) corridors are reportedly even higher, with the report noting that fees extracted by intermediaries translate directly into lost food and working capital for African households.
UPI's Global Footprint
The Zimbabwe talks reflect a broader international momentum behind India's payments architecture. UPI handled roughly 49% of global real-time payment volumes in 2025 and powered 84% of India's own digital payments in the last fiscal year, according to government data. NIPL has already exported UPI-style infrastructure to several countries, and this global reach is now being extended further into Africa.
Beyond Zimbabwe, the nations of Ghana, Uganda, Rwanda, and Mozambique have reportedly signalled interest in collaboration with NPCI. The report observed that early adopters will set technical standards that later entrants are likely to inherit, giving first movers a structural advantage in shaping the continent's digital payments ecosystem.
What Happens Next
If negotiations are concluded by the 31 October deadline as indicated, Zimbabwe would join a growing list of nations that have licenced or are piloting UPI-based infrastructure. Industry watchers will be tracking whether the agreement covers a full domestic interoperability stack, cross-border remittance corridors, or both — and whether NIPL's deployment model in Zimbabwe offers a replicable template for the rest of southern Africa.
Point of View
But the hard work lies in interoperability with mobile-money incumbents who have no incentive to cede market position. The 31 October deadline sounds ambitious; what matters more is whether any agreement covers cross-border remittance corridors, not just domestic clearing. With Ghana, Uganda, Rwanda, and Mozambique also circling, the first mover really will set the standard — meaning India's approach to licensing terms could shape African fintech infrastructure for a decade.
NationPress
10 Oct 2026
Frequently Asked Questions
What is the UPI deal Zimbabwe is reportedly considering?
Zimbabwe is in talks with NPCI International Payments Ltd to licence the technology behind India's Unified Payments Interface (UPI) as a shared domestic rail for real-time payments. The deal would allow banks, mobile-money operators, and fintechs to clear transactions on a single public layer, reducing costs and increasing speed.
When could the Zimbabwe-NPCI negotiations be concluded?
Reserve Bank of Zimbabwe governor John Mushayavanhu indicated that negotiations with NPCI International could be concluded by 31 October 2026, though no final agreement has been announced.
Why does Zimbabwe need a new payments rail?
Despite processing 238 million electronic transactions in Q4 2025 — with mobile money accounting for 87% of volume — Zimbabwe lacks a low-cost common interoperability layer. A UPI-style rail would reduce fragmentation and cut transaction fees for consumers and businesses.
How significant are remittances to Zimbabwe, and what does this deal mean for them?
Diaspora remittances reached $2.45 billion in 2025, averaging $6.7 million a day, and are Zimbabwe's second-largest source of foreign exchange after mining. A UPI-based rail with cross-border capability could lower the high cost of sending money — sub-Saharan Africa's average was near 8% in 2025 versus an SDG target of 3%.
Which other African countries are interested in India's UPI infrastructure?
Ghana, Uganda, Rwanda, and Mozambique have reportedly signalled interest in collaboration with NPCI International. Analysts note that early adopters will set the technical standards that later entrants are likely to inherit.