GST Council meeting: Industry pushes for input tax credit fixes, less litigation
Synopsis
Ahead of the GST Council's next meeting, industry body PHDCCI has put forward a sweeping reform agenda — led by a push to protect honest ITC recipients from supplier defaults, ease blocked credits, bar low-value notices, and streamline the new GST Appellate Tribunal. With the Finance Minister signalling a process-only session, how much of this legislative wishlist gets traction is the real question.
Key Takeaways
PHDCCI submitted its GST Council expectations on 5 October 2026 , covering input tax credit, litigation reduction, and tribunal reforms.
Industry wants Section 16(2)(c) amended so bona fide recipients retain ITC, with recovery directed first at the defaulting supplier .
Relaxation of blocked credits under Section 17(5) sought for motor vehicles, food, beverages, catering, and travel benefits.
A bar on tax notices where the demand is below ₹10,000 — covering an estimated 20% of cases by number — has been proposed.
Industry also wants cross-GSTIN credit transfers within the same PAN and a time-bound refund mechanism for stranded cess balances.
The Finance Minister has said the meeting will focus on process reforms under 'Next-Gen GST' ; no rate changes are expected after the September 2025 rationalisation.
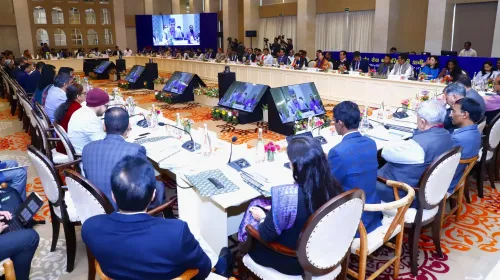
Industry bodies on Monday, 5 October 2026 laid out a detailed wishlist ahead of the upcoming GST Council meeting, urging the Council to overhaul input tax credit (ITC) rules, extend statutory safe-harbour protections to bona fide recipients, and sharply cut the volume of tax litigation burdening businesses across India.
Key Demands on Input Tax Credit
The PHD Chamber of Commerce and Industry (PHDCCI) submitted a formal list of expectations, with amendments to Section 16(2)(c) topping the agenda. Under the proposed change, a recipient holding a valid invoice — having received the supply, paid through banking channels, and not involved in any collusion — would retain input tax credit, with recovery action directed first against the defaulting supplier rather than the recipient. This single amendment, industry argues, would eliminate a large class of disputes where honest buyers are penalised for supplier defaults.
Industry also seeks a significant relaxation of blocked credits under Section 17(5), currently applicable to motor vehicles, food and beverages, outdoor catering, beauty and health services, club memberships, and travel benefits. The ask is for credit eligibility to extend to all business-use expenditure duly recorded in company books.
Cutting Litigation and Easing Settlements
Reducing litigation is a central theme of the industry submission. PHDCCI has called for clear transitional language covering interest- and penalty-only demands as well as Rule 142 / DRC-07 recoveries, a grey area that has spawned numerous disputes. It also wants amounts paid on voluntary settlement to be classified as a 'charge' rather than an admission of liability, thereby removing the stigma and collateral legal consequences currently attached to such payments.
Ashok Kumar Batra, Chair of the Indirect Taxes Committee at PHDCCI, additionally called for a time-bound mechanism to utilise or refund cess balances stranded following the discontinuance of the cess.
Cross-GSTIN Credit and Notice Thresholds
Another sought-after reform is the freedom to move input tax credit across GSTINs of the same PAN holder — a practical pain point for large enterprises with multiple state-level registrations that accumulate credit in units with low output liability. The current framework forces credit to sit idle, effectively locking working capital.
On the litigation-reduction front, industry has proposed barring the issuance of notices where the tax demand falls below ₹10,000, a threshold estimated to cover roughly 20% of cases by number. The proposal would also extend to pending adjudications and appeals, potentially clearing a significant backlog.
GST Appellate Tribunal Reforms
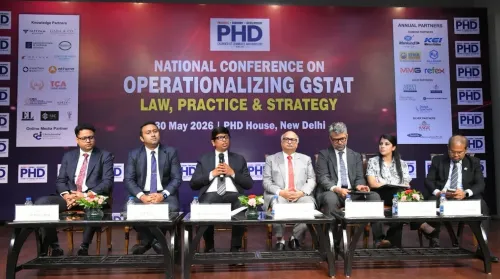
With the GST Appellate Tribunal (GSTAT) becoming operational, PHDCCI flagged expectations around uniform e-filing, clarity on pre-deposit adjustment, clubbing of appeals under Rule 18 of the GSTAT Rules, and the introduction of a departmental monetary threshold for filing appeals — steps that would prevent the government from flooding the Tribunal with low-value matters.
What the Government Has Said
Union Finance Minister Nirmala Sitharaman has publicly indicated that the forthcoming GST Council session will focus exclusively on process reforms under the 'Next-Gen GST' agenda. No fresh rate proposals are expected following the two-slab rationalisation that came into effect on 9 September 2025. The government's stated emphasis on administrative streamlining broadly aligns with several of PHDCCI's asks, though the extent to which legislative changes — such as Section 16(2)(c) amendments — will be taken up remains to be seen.
Point of View
But its most consequential ask — amending Section 16(2)(c) — requires legislative action that the Council cannot deliver on its own; it needs Parliament. The Finance Minister's 'process reforms only' framing may be a signal that industry's harder legislative asks will be deferred again, as they were at multiple previous Councils. The ₹10,000 notice threshold proposal is administratively straightforward and could meaningfully reduce tribunal load, yet it has been floated before without traction. Until the Centre puts a credible legislative timeline on Section 16 amendments, the ITC litigation overhang — one of the biggest complaints from mid-sized businesses — will persist.
NationPress
5 Oct 2026
Frequently Asked Questions
What is the key input tax credit demand ahead of the GST Council meeting?
Industry wants Section 16(2)(c) of the GST Act amended so that a recipient who holds a valid invoice, has received the supply, and paid through banking channels retains input tax credit even if the supplier defaults on tax payment. Under this proposal, recovery would be directed first against the defaulting supplier, not the buyer.
What are blocked credits under Section 17(5) and why does industry want them relaxed?
Section 17(5) of the GST Act lists categories of expenditure — including motor vehicles, food and beverages, outdoor catering, beauty and health services, club memberships, and travel benefits — for which input tax credit is currently not allowed. Industry argues that credit should be available for all business-use expenditure recorded in company books, regardless of category.
What is the proposal to reduce GST litigation?
PHDCCI has proposed barring tax notices where the demand is below ₹10,000, estimated to cover about 20% of all cases by number. The industry body has also called for clear transitional rules on interest- and penalty-only demands and Rule 142/DRC-07 recoveries to prevent disputes in these grey areas.
What reforms has industry sought for the GST Appellate Tribunal?
Industry has asked for uniform e-filing at the GST Appellate Tribunal (GSTAT), clarity on pre-deposit adjustment, clubbing of appeals under Rule 18 of the GSTAT Rules, and a departmental monetary threshold that would prevent the government from filing appeals in low-value matters.
Will the GST Council take up rate changes at the upcoming meeting?
No. Union Finance Minister Nirmala Sitharaman has publicly stated that the upcoming GST Council session will focus only on process reforms under the 'Next-Gen GST' agenda. No rate proposals are expected following the two-slab rationalisation that took effect on 9 September 2025.