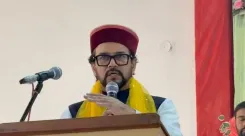
RBI Deputy Governor Murmu flags 5 growth priorities for NBFC sector
Synopsis
As NBFC credit crosses 16.7% of nominal GDP, RBI Deputy Governor Shirish Chandra Murmu has drawn a clear five-point map for the sector: governance culture, liquidity discipline, asset quality, customer protection, and cyber resilience. The message is unambiguous — the sector's rapid growth will attract proportionally tighter regulatory scrutiny.
Key Takeaways
RBI Deputy Governor Shirish Chandra Murmu outlined five priorities for NBFCs and HFCs in the RBI Bulletin for September 2026 .
NBFC credit stands at 16.7% of nominal GDP , up from 15.9% a year earlier, and equals roughly 27% of Scheduled Commercial Bank credit.
The five areas are: governance , liquidity risk management , asset quality , customer protection , and digital transformation and cyber resilience .
Murmu called for securitisation to mature into a genuine risk-transfer tool, not just a liquidity instrument.
He urged wider use of AI and machine learning for early detection of borrower stress, while warning that growth must not compromise underwriting standards.
The RBI's recent recovery-agent conduct guidelines were cited as evidence of the regulator's focus on customer protection.
Reserve Bank of India (RBI) Deputy Governor Shirish Chandra Murmu has outlined five critical areas for sustainable growth in the non-banking financial company (NBFC) and housing finance company (HFC) sector, as it navigates a shift from being alternative lenders to becoming specialised financial partners. The priorities were published in the RBI Bulletin for September 2026, underscoring the regulator's sharpening focus on a sector whose credit footprint continues to expand.
NBFC credit now stands at 16.7% of nominal GDP, up from 15.9% a year earlier, and accounts for roughly 27% of credit extended by Scheduled Commercial Banks, compared with 26% the previous year. The steady rise signals both growing systemic importance and the need for tighter guardrails.
Governance and Compliance Culture
Murmu placed sound governance at the top of the agenda. 'Good governance is the foundation of every strong institution. Boards and senior management must build a culture of sustained compliance and ethics across the organisation. As the sector scales, that strength must scale with it,' he said. The message was directed particularly at larger NBFCs whose rapid expansion has at times outpaced internal controls.
Liquidity Risk Management
The second priority is liquidity management, an area where past stress events — including episodes in some advanced economies — have exposed the vulnerability of NBFCs and HFCs to sudden shifts in market sentiment and funding concentration. 'Strong liquidity risk management is not optional,' Murmu wrote, calling on entities to diversify funding sources. He also flagged the need for a deeper, more liquid corporate bond market and said the RBI would continue working with market participants toward that goal. Separately, he noted that securitisation should evolve beyond a liquidity instrument into a genuine mechanism for risk transfer, backed by proper skin-in-the-game and transparency rules.
Asset Quality and Credit Discipline
With credit growth accelerating, Murmu stressed the third priority: protecting asset quality. He called for rigorous stress testing, early-warning systems, and dynamic provisioning, and encouraged greater use of AI and machine learning tools to detect early signs of borrower stress. 'Let me be clear: growth must never come at the cost of underwriting standards,' he stated. This comes amid broader concerns from the RBI about pockets of overleveraging in the retail and unsecured lending segments.
Customer Protection and Conduct
The fourth area is customer trust. Murmu emphasised that the pace of financial innovation must not outstrip the protection of customers, particularly vulnerable ones. 'Conduct regulation, grievance redressal, and responsible lending remain top priorities for us. Our recent guidelines on conduct of recovery agents reflect this priority. In an age where feedback travels instantly, there is no substitute for public trust,' he said. The reference to recovery-agent guidelines points to a specific regulatory action the RBI has taken in recent months to address coercive collection practices.
Digital Transformation and Cyber Resilience
The fifth priority is digital transformation, with the Deputy Governor urging NBFCs to deepen technology adoption — from blockchain in supply chain finance to AI in fraud detection. However, he coupled the call for innovation with a clear warning: 'Digitalisation brings cyber risk. Cyber resilience must stay a top priority. Entities must invest in strong cyber security to protect customer data and maintain trust. Innovation must serve both efficiency and fairness,' Murmu stressed.
The statement arrives as the RBI tightens its supervisory framework for the sector, and as several large NBFCs prepare for potential transition to the bank licensing route. How the sector responds to these five imperatives is likely to shape both its regulatory treatment and its long-term growth trajectory.
Point of View
Not just an individual institution's. The emphasis on securitisation reform and corporate bond market depth signals that the RBI is thinking structurally — past NBFC stress events were as much a market-infrastructure failure as a firm-level one. The cyber-resilience push is overdue: many mid-sized NBFCs have digitised front-ends without hardening back-ends, and one significant breach could undo years of customer trust-building.
NationPress
26 Sept 2026
Frequently Asked Questions
What are the five growth priorities RBI Deputy Governor Murmu outlined for NBFCs?
Murmu identified governance and compliance culture, liquidity risk management, asset quality and credit discipline, customer protection and conduct, and digital transformation with cyber resilience as the five priorities for the NBFC and HFC sector, as published in the RBI Bulletin for September 2026.
How large is the NBFC sector relative to the Indian economy?
NBFC credit currently stands at 16.7% of nominal GDP, up from 15.9% a year earlier. The sector also accounts for approximately 27% of total credit extended by Scheduled Commercial Banks, compared with 26% the previous year.
Why did Murmu stress liquidity management for NBFCs?
Past stress events in the NBFC sector and in some advanced economies have shown how exposed these entities can be to sudden changes in market sentiment and concentrated funding sources. Murmu called liquidity risk management 'not optional' and urged NBFCs to diversify funding while the RBI works to deepen the corporate bond market.
What did the RBI say about AI and technology use in the NBFC sector?
Murmu encouraged NBFCs to adopt AI and machine learning tools for early detection of borrower stress and fraud, while also deploying blockchain in supply chain finance. He coupled this with a strong warning that digitalisation brings cyber risk, and that entities must invest in robust cyber security to protect customer data.
What is the RBI's stance on customer protection in the NBFC sector?
Customer trust is one of Murmu's five explicit priorities. He stressed that conduct regulation, grievance redressal, and responsible lending are top priorities for the RBI, pointing to recently issued guidelines on recovery-agent conduct as a concrete example of the regulator's focus on protecting, especially, vulnerable borrowers.