HAL Q2 FY27 profit rises 16% to ₹1,936 crore; margins under pressure
Synopsis
HAL posted a solid 16 per cent profit jump in Q2 FY27, but the real story is margin compression — costs climbed faster than revenues, narrowing the EBITDA margin and triggering a 4 per cent intraday stock slide. CLSA's bullish counter-call, pegging a revised target of ₹5,625 on imminent LCA Mk1A deliveries, sets up a classic results-day tug-of-war between near-term cost pressure and long-term indigenisation upside.
Key Takeaways
HAL reported a 16% YoY rise in Q2 FY27 net profit to ₹1,936 crore , up from ₹1,669 crore in Q2 FY26.
Revenue from operations grew 14.8% to ₹7,613 crore .
EBITDA margin narrowed to 22.8% from 23.5% as total expenses rose to ₹6,132 crore .
HAL shares fell up to 4.15% intraday to ₹4,738.80 before partially recovering.
CLSA raised its target price to ₹5,625 and retained an 'Outperform' rating, citing expected LCA Mk1A deliveries.
The stock has surged over 582% in the past five years and gained around 10% year-to-date.
Hindustan Aeronautics Limited (HAL) on Thursday, 12 November 2026 reported a 16 per cent year-on-year rise in consolidated net profit to ₹1,936 crore for the second quarter ended September 2026 (Q2 FY27), driven by healthy revenue growth. However, margin compression and rising expenses weighed on investor sentiment, sending the stock lower during the session.
Key Financial Highlights
Net profit climbed from ₹1,669 crore in Q2 FY26 to ₹1,936 crore this quarter, according to the company's stock exchange filing. Revenue from operations grew 14.8 per cent year-on-year to ₹7,613 crore, up from ₹6,629 crore in the year-ago period — a solid topline performance for the state-run aerospace and defence manufacturer.
Margin Pressure and Rising Costs
Operating performance, however, told a more cautious story. Earnings before interest, tax, depreciation and amortisation (EBITDA) rose 11.6 per cent year-on-year to ₹1,739 crore, but the EBITDA margin narrowed to 22.8 per cent from 23.5 per cent in Q2 FY26. Total expenses climbed sharply to ₹6,132 crore from ₹5,296 crore a year earlier, squeezing profitability even as revenues expanded.
Market Reaction
HAL shares fell as much as 4.15 per cent intraday to a low of ₹4,738.80 per share on the results day. By noon trade, the stock had partially recovered, trading 2.45 per cent lower at ₹4,822.65. The post-results dip reflects investor concern over the margin trajectory, even as the headline profit number came in positive.
CLSA Retains Outperform, Raises Target Price
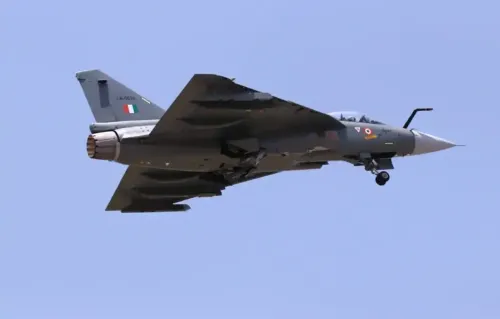
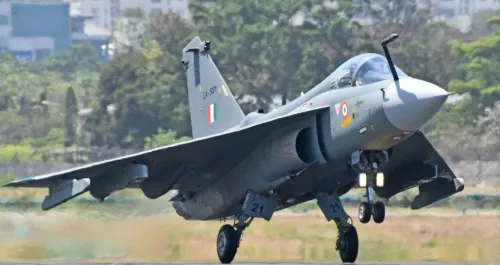
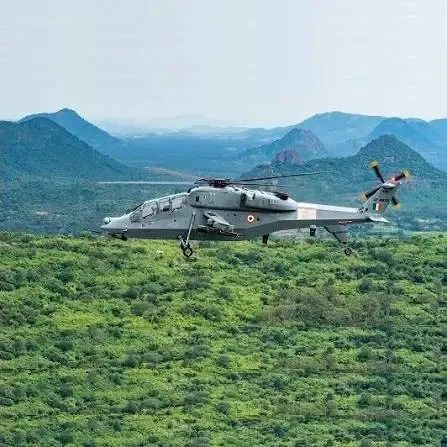
Despite the intraday selloff, brokerage firm CLSA maintained a constructive stance on the defence major. The foreign brokerage raised its target price on HAL to ₹5,625 from ₹5,581 and retained its 'Outperform' rating. CLSA noted it expects deliveries of the Light Combat Aircraft (LCA) Mk1A to commence soon, adding that recent remarks by Air Chief Marshal A.P. Singh on restoring the Indian Air Force's combat strength to its sanctioned level indicate the programme faces no fundamental hurdles. The brokerage also cited the government's push for defence indigenisation under the Make in India initiative as gaining traction.
Long-Term Investor Returns Remain Strong
Zooming out, HAL's long-term stock performance remains impressive. The stock has surged over 582 per cent in the last five years and more than doubled over the past three years. On a year-to-date basis, shares have gained around 10 per cent. This comes amid a broader re-rating of Indian defence stocks as the government accelerates indigenisation targets and expands capital procurement budgets. The next quarter will be closely watched for signs that HAL can stabilise margins while sustaining revenue momentum as LCA Mk1A deliveries potentially begin.
Point of View
Outpacing EBITDA growth and compressing margins in a business where cost discipline is as critical as order inflows. The irony is that the very programme that could unlock HAL's next leg of growth — the LCA Mk1A — has been a years-long delivery overhang; CLSA's optimism on 'imminent' deliveries has surfaced before. For long-term investors, the indigenisation story remains intact, but the market's 4 per cent intraday reaction signals that patience with execution slippages is thinning.
NationPress
12 Nov 2026
Frequently Asked Questions
What was HAL's net profit in Q2 FY27?
Hindustan Aeronautics Limited reported a consolidated net profit of ₹1,936 crore in Q2 FY27 (quarter ended September 2026), a 16 per cent increase from ₹1,669 crore in the same quarter last year. Revenue from operations also rose 14.8 per cent to ₹7,613 crore.
Why did HAL's share price fall after the Q2 results?
HAL shares fell as much as 4.15 per cent intraday to ₹4,738.80 despite the profit growth, as investors reacted to narrowing EBITDA margins and a sharp rise in total expenses. The EBITDA margin slipped to 22.8 per cent from 23.5 per cent a year earlier.
What is CLSA's view on HAL after the Q2 results?
CLSA retained its 'Outperform' rating on HAL and raised its target price to ₹5,625 from ₹5,581. The brokerage cited expected commencement of LCA Mk1A deliveries and the government's Make in India defence push as key positive catalysts.
What is the LCA Mk1A and why does it matter for HAL?
The Light Combat Aircraft (LCA) Mk1A is an advanced variant of India's domestically developed Tejas fighter jet, ordered by the Indian Air Force. Its deliveries are considered a major near-term revenue trigger for HAL, and Air Chief Marshal A.P. Singh has publicly backed restoring the IAF's combat strength, signalling sustained demand.
How has HAL stock performed over the long term?
HAL shares have surged over 582 per cent in the last five years and more than doubled in the past three years, reflecting a broad re-rating of Indian defence stocks. On a year-to-date basis, the stock has gained approximately 10 per cent as of 12 November 2026.