India retail leasing hits 2.22 MSF in Q3 2026 across top 8 cities
Synopsis
India's retail sector leased 2.22 MSF in Q3 2026, but the real story is in where demand is going — main streets surged 33% YoY while mall leasing collapsed 37.8%, because Grade A mall vacancy has tightened below 5% for the third straight quarter with zero new supply. A 12.7 MSF pipeline through 2028 could reshape the market, but for now, domestic brands are snapping up every premium main-street slot they can find.
Key Takeaways
India's retail gross leasing volume (GLV) reached 2.22 MSF in Q3 2026 across the top 8 cities , per Cushman & Wakefield .
Leasing moderated 7.3% QoQ and 4.4% YoY , but YTD volumes of 6.57 MSF remain nearly flat — up just 0.4% over last year.
Main streets dominated at 67.9% of volumes ( 1.51 MSF ), surging 33.1% YoY , while mall leasing fell 37.8% YoY .
Grade A mall vacancy has tightened below 5% with no new supply for three consecutive quarters .
Domestic retailers drove 86.3% of leasing activity; Delhi NCR led cities with a 24.9% share.
A pipeline of 12.7 MSF of Grade A mall supply is expected through 2028 , led by Delhi NCR , Bengaluru , and Chennai .
India's retail real estate sector recorded a gross leasing volume (GLV) of 2.22 million square feet (MSF) across the top eight cities in Q3 2026, according to a report released on Thursday, 1 October 2026 by property consultancy Cushman & Wakefield. While occupier demand remained active, leasing moderated by 7.3 per cent quarter-on-quarter (QoQ) and 4.4 per cent year-on-year (YoY).
Year-to-Date Leasing Remains Stable
Retail leasing for the year touched 6.57 MSF on a year-to-date (YTD) basis, representing a marginal 0.4 per cent increase over the same period last year. According to the Cushman & Wakefield report, this broadly stable trajectory signals sustained retailer demand even as the market recorded no new Grade A mall supply for the third consecutive quarter — a supply-side constraint that is increasingly shaping leasing patterns.
Main Streets Outpace Malls
Main street locations dominated leasing activity, accounting for 67.9 per cent of total volumes at 1.51 MSF — up 29.3 per cent QoQ and 33.1 per cent YoY. The surge reflects retailer appetite for prominent, high-visibility locations where footfall and brand exposure are more predictable.
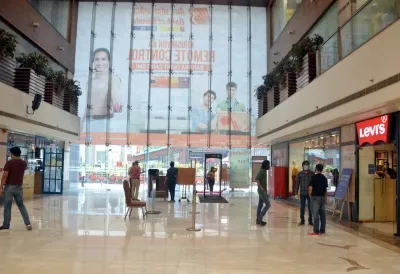
Mall leasing, by contrast, accounted for the remaining 32.1 per cent at 0.71 MSF, with volumes falling 42.1 per cent QoQ and 37.8 per cent YoY. Grade A mall vacancy has tightened to below 5 per cent, underscoring just how constrained quality mall space has become across key urban markets.
Supply Pipeline and Key Markets
Relief on the supply side is expected, with nearly 12.7 MSF of Grade A mall supply projected through 2028. The pipeline will be led by Delhi NCR, followed by Bengaluru and Chennai, with approximately 1.35 MSF slated for completion in 2026 alone.
Geographically, Delhi NCR, Hyderabad, and Mumbai collectively accounted for 61 per cent of overall Q3 activity. Delhi NCR led with 0.55 MSF and a 24.9 per cent share, followed by Hyderabad at 0.45 MSF and Mumbai at 0.35 MSF.
Domestic Retailers Drive Demand
Domestic retailers maintained a commanding position, accounting for 86.3 per cent of leasing activity at 1.92 MSF — a reflection of continued expansion by home-grown brands. International retailers contributed the remaining 13.7 per cent, with volumes of 0.3 MSF.
Gautam Saraf, Executive Managing Director – Mumbai & New Business, Cushman & Wakefield, noted: 'India's retail market continues to demonstrate steady underlying occupier interest, even as quality retail space remains constrained. While leasing moderated during the quarter, year-to-date activity remains largely in line with last year, with a slight increase.'
Saraf also pointed to the upcoming festive season as a potential tailwind: 'As we enter the festive period, we expect strong consumption sentiment to provide an additional tailwind for retailers and reinforce the underlying demand environment.'
What to Watch
With the festive quarter underway and a sizeable Grade A mall pipeline expected to materialise over the next two years, the interplay between supply unlocking and retailer demand will be the key variable to watch. If Grade A vacancy tightens further before new supply arrives, main street leasing premiums could rise — adding cost pressure for brands seeking high-footfall locations in metro markets.
Point of View
And vacancy below 5% means demand is being rationed rather than freely expressed. Main street leasing surging 33% YoY is partly a demand signal and partly a displacement effect — retailers who would prefer malls are settling for high streets because there is simply no mall space to lease. The 12.7 MSF pipeline through 2028 is consequential, but delivery timelines for Indian commercial real estate projects have historically slipped. If the festive quarter generates the consumption tailwind Cushman & Wakefield anticipates, expect vacancy to tighten further before supply arrives — and leasing costs on prime main streets to rise accordingly.
NationPress
1 Oct 2026
Frequently Asked Questions
What was India's retail leasing volume in Q3 2026?
India's retail gross leasing volume (GLV) reached 2.22 million square feet (MSF) in Q3 2026 across the top eight cities, according to a Cushman & Wakefield report released on 1 October 2026. On a year-to-date basis, total leasing stood at 6.57 MSF — up a marginal 0.4% over the same period last year.
Why is mall leasing falling while main street leasing is rising?
Mall leasing fell 42.1% QoQ and 37.8% YoY in Q3 2026 primarily because Grade A mall vacancy has tightened to below 5%, with no new mall supply entering the market for three consecutive quarters. Retailers have consequently shifted to high-visibility main street locations, driving a 33.1% YoY rise in main street leasing volumes.
Which cities led retail leasing activity in Q3 2026?
Delhi NCR led with 0.55 MSF and a 24.9% share of total leasing, followed by Hyderabad at 0.45 MSF and Mumbai at 0.35 MSF. Together, the three cities accounted for 61% of overall Q3 2026 retail leasing activity.
How much new Grade A mall supply is expected in India?
Approximately 12.7 MSF of Grade A mall supply is projected to enter the market through 2028, with Delhi NCR leading the pipeline, followed by Bengaluru and Chennai. Around 1.35 MSF is expected to be completed within 2026 itself, which should gradually ease current supply constraints.
What is the outlook for India's retail real estate market?
Cushman & Wakefield expects the upcoming festive season to provide a consumption tailwind that reinforces underlying retailer demand. Over the medium term, the 12.7 MSF Grade A mall pipeline through 2028 is expected to improve quality space availability, though current vacancy levels below 5% indicate the market remains supply-constrained for now.