57th GST Council meet: Nasscom seeks export clarity on overseas branches, R&D
Synopsis
With the 57th GST Council finally convening after two deferrals, Nasscom is pressing for overdue clarity on two tax ambiguities that have haunted Indian IT exporters for years — whether branch-delivered services qualify as exports, and whether R&D work on foreign prototypes done in India counts. The answers could unlock working capital and reduce litigation for one of India's most valuable export industries.
Key Takeaways
Nasscom has raised two GST export-treatment issues ahead of the 57th GST Council meeting on 8 October 2026 .
The first issue concerns services delivered from India through overseas branches , which currently risk losing export status compared with subsidiary-routed exports.
The second issue covers R&D, engineering, and testing services performed in India on prototypes from foreign customers, which are presently classified as domestic supply rather than exports.
Nasscom VP Ashish Aggarwal said clarity would 'release working capital and reduce litigation' for Indian IT exporters.
Progress has been made: the Council's 2021 clarification on GCC services and removal of the intermediary provision this year settled earlier disputes.
The meeting was originally set for 12 September , postponed twice — first due to the BRICS summit , then rescheduled again to 8 October .
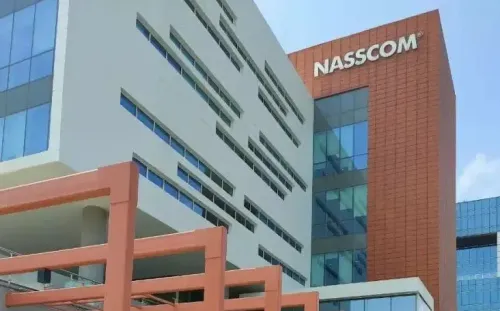
Ahead of the 57th GST Council meeting rescheduled for Thursday, 8 October 2026, technology industry body Nasscom has urged the Council to resolve two long-standing ambiguities in the GST treatment of services exports — specifically around services delivered through overseas branches and R&D, engineering, and testing work performed in India on prototypes supplied by foreign customers.
The Overseas Branch Issue
Nasscom Vice President and Head of Public Policy Ashish Aggarwal said the way a company structures its overseas presence should not determine whether a service supplied from India qualifies as an export. Indian service exporters frequently serve foreign customers through branches based abroad, and under the current framework such arrangements can jeopardise export status, triggering input tax credit reversals and adding to the compliance burden.
'Clarity on this would support competitiveness, release working capital and reduce the litigation the industry has faced over the years,' Aggarwal said.
According to Nasscom, the existing rules create a disparity between exports routed through overseas branches and those delivered through subsidiaries — a structural inconsistency that has become a source of protracted litigation for Indian IT-ITES exporters.
R&D and Engineering Services: The Export Status Dispute
The second concern relates to R&D, engineering, and testing services carried out in India on prototypes or samples provided by overseas customers. Under current GST rules, such services are treated as being supplied in India — where the physical work is performed — and therefore do not qualify as exports.
Nasscom argues this classification is misaligned with economic reality: the overseas customer receives and uses the results abroad, and the service should consequently qualify as an export. Aggarwal warned that as artificial intelligence (AI) and other technologies expand the range of services that can be delivered remotely from India, the absence of clarity now risks fuelling disputes in the future.
'As AI and other technologies widen the range of services delivered from India, clarity on this point now would help prevent future disputes,' he said.
What Progress Has Been Made
Nasscom acknowledged that the industry and the government have been engaged on GST export-treatment issues for several years, and that meaningful progress has been made. The Council's 2021 clarifications settled the export status of services provided by global capability centres (GCCs) to their overseas group companies, and the removal of the intermediary provision earlier this year addressed a long-standing pain point for IT-BPM companies.
India's technology sector — including the fast-growing GCC segment — holds significant potential in technology-enabled services and R&D, Nasscom said, making the outstanding ambiguities a priority for resolution.
Why the Meeting Was Rescheduled Twice
The 57th GST Council meeting was originally scheduled for 12 September but was postponed to 7 October due to the BRICS summit. It was subsequently rescheduled again to 8 October, according to an office memorandum issued by the GST Council Secretariat. The two-time deferral has extended the wait for an industry that has sought resolution on these issues through multiple Council cycles.
What the Industry Is Watching
With the Council now convening on Thursday, the tech sector will be looking for formal clarifications or a committee referral on both the branch-office export question and the R&D services classification. Any Council guidance is expected to reduce litigation, ease working capital cycles, and signal to global technology firms that India's regulatory framework is aligned with its ambitions as a hub for high-value services exports.
Point of View
GCCs, and cross-border prototype work — is becoming a competitive liability. Every ambiguity translates into a working capital hit and a litigation risk that global tech firms factor into location decisions. The Council has, to its credit, made incremental progress since 2021; but iterative clarifications are no substitute for a coherent, future-proofed rule that accounts for AI-era service delivery. With India pushing hard to grow its GCC base and high-value R&D exports, this is precisely the kind of friction that a Council meeting should resolve rather than defer again.
NationPress
7 Oct 2026
Frequently Asked Questions
What are the two GST issues Nasscom has raised at the 57th Council meeting?
Nasscom has flagged ambiguity over whether services exported from India through overseas branches qualify as exports for GST purposes, and whether R&D, engineering, and testing services performed in India on prototypes supplied by foreign customers should be classified as exports. Both issues have led to litigation and working capital strain for Indian IT exporters.
Why does the overseas branch structure matter for GST export status?
Under current rules, services routed through overseas branches may not qualify as exports, while the same services delivered through a subsidiary do qualify — creating an uneven playing field. This can force companies to reverse input tax credits and adds to compliance costs, according to Nasscom.
Why are R&D services on foreign prototypes not treated as exports currently?
GST rules generally treat a service as supplied in India when the work is physically performed here, regardless of where the customer uses the result. Nasscom argues this misclassifies services whose economic benefit flows entirely to an overseas customer, and that they should therefore qualify as exports.
What progress has already been made on GST and IT services exports?
The GST Council's 2021 clarifications confirmed export status for services provided by global capability centres to their overseas group companies. This year, removal of the intermediary provision resolved a long-standing dispute for IT-BPM companies. Nasscom says two structural gaps remain outstanding.
Why was the 57th GST Council meeting delayed twice?
The meeting was originally scheduled for 12 September 2026 but was first postponed to 7 October due to the BRICS summit, and then rescheduled again to 8 October 2026, according to an office memorandum from the GST Council Secretariat.