Goyal: Govt extends Stand-Up India, PMMY credit schemes to 2031
Synopsis
The Modi government has extended the Stand-Up India Scheme and the PMMY Credit Guarantee Fund for Micro Units by five years to March 2031, with combined corpus funding of over ₹9,111 crore, targeting women, SC/ST entrepreneurs, and micro-business owners.
Key Takeaways
Five-year extension approved for both Stand-Up India and PMMY Credit Guarantee Fund, running until March 2031 .
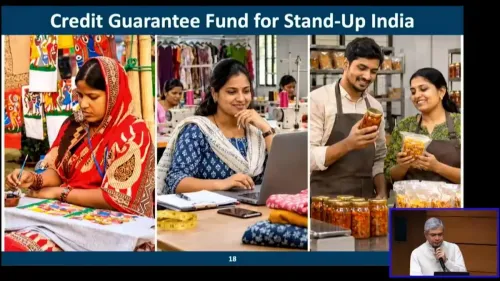
Stand-Up India gets a Credit Guarantee Corpus of ₹4,111 crore , targeting at least 2.5 lakh new greenfield enterprises by women and SC/ST borrowers.
PMMY Credit Guarantee Fund receives a corpus of ₹5,000 crore to support collateral-free loans for small shopkeepers and micro-business owners.
Stand-Up India was originally launched in April 2016 ; PMMY in April 2015 — both now have over a decade of operational history.
The guarantee corpus unlocks a multiple of its face value in actual bank lending, as the fund covers lender risk rather than disbursing directly.
Union Minister Piyush Goyal framed the announcement as a direct call to action for aspiring entrepreneurs sitting on unexecuted business plans.
A combined credit guarantee corpus of over ₹9,000 crore is now pointed squarely at India's most underserved entrepreneurs — and they have five more years to use it. Union Commerce and Industry Minister Piyush Goyal announced on Wednesday, November 11, 2026, that the government has approved a five-year extension until March 2031 for two of its flagship small-business credit schemes, the Stand-Up India Scheme and the Credit Guarantee Fund for Micro Units under PMMY.
What the two extensions actually do
The Stand-Up India Scheme — originally launched in April 2016 to push formal bank credit toward women and SC/ST entrepreneurs — gets a fresh Credit Guarantee Corpus of ₹4,111 crore. The stated ambition: bring at least 2.5 lakh new entrepreneurs into the banking system to launch greenfield enterprises, meaning first-time ventures with no prior track record to lean on. That is precisely the gap a guarantee fund is built to bridge — when a first-generation founder cannot offer collateral, the corpus steps in so the bank still lends.
The second extension targets the other end of the micro-economy. The Credit Guarantee Fund for Micro Units, operating under the Pradhan Mantri Mudra Yojana (PMMY) framework — itself launched in April 2015 — receives a freshly approved corpus of ₹5,000 crore. The design is deliberately collateral-free: small shopkeepers and micro-business owners can borrow and expand without having to pledge assets they may not own.
A decade of layered credit architecture
These are not new schemes being invented — they are battle-tested frameworks being refuelled. Stand-Up India and PMMY together represent over a decade of the central government's deliberate effort to pull marginalised borrowers into formal credit channels, reducing their dependence on informal moneylenders who charge multiples of bank rates.
What Wednesday's announcement signals is institutional confidence: the architecture works well enough to extend, the guarantee corpus needs replenishment, and the target demographic — women founders, SC/ST entrepreneurs, micro-shopkeepers — remains a priority constituency for the Modi government's economic inclusion agenda. The combined ₹9,111 crore corpus is not a loan disbursement; it is a guarantee reserve that unlocks a multiple of that figure in actual bank lending.
Who stands to benefit — and by when
Minister Goyal addressed potential beneficiaries directly in the post, writing: 'If you or someone in your network has been sitting on a business plan, waiting for the right financial opportunity, this is your sign to dust it off.' The runway now extends to March 2031 — roughly four and a half years — giving first-time founders, particularly women and those from SC/ST communities, a stable policy window to plan, apply, and launch.
The schemes operate through scheduled commercial banks, regional rural banks, and microfinance institutions, meaning the access point is a local branch, not a distant ministry window. For aspirant entrepreneurs in Tier-2 and Tier-3 India, that distribution reach is as important as the corpus size itself.
India's MSME sector already accounts for a substantial share of GDP and employment. Keeping the credit guarantee infrastructure funded and extended does not just support individual businesses — it props up the broader jobs machine at a time when formal employment creation remains a central political and economic challenge. Watch for parliamentary updates on utilisation targets and any mid-term corpus review as the schemes move toward 2028–29.
Point of View
The government signals institutional confidence in the existing delivery pipeline through banks and regional rural lenders. The explicit targeting of women and SC/ST entrepreneurs through Stand-Up India also carries a political calculus: it allows the BJP to demonstrate tangible economic inclusion ahead of election cycles. The key variable to watch is utilisation quality — how many of the 2.5 lakh targeted loans actually fund viable greenfield businesses versus refinancing existing informal debt.
NationPress
11 Nov 2026
Frequently Asked Questions
What is the Stand-Up India Scheme and who can apply?
Stand-Up India is a government scheme launched in 2016 to provide bank loans for greenfield enterprises. It is specifically designed for women entrepreneurs and entrepreneurs from Scheduled Caste or Scheduled Tribe communities. With the latest extension, it runs until March 2031 and has a Credit Guarantee Corpus of ₹4,111 crore.
What is the PMMY Credit Guarantee Fund for Micro Units?
The Credit Guarantee Fund for Micro Units operates under the Pradhan Mantri Mudra Yojana (PMMY) framework, launched in 2015. It enables small shopkeepers and micro-business owners to access collateral-free loans through banks and microfinance institutions. The government has approved a fresh corpus of ₹5,000 crore and extended the scheme to March 2031.
How long have Stand-Up India and PMMY been extended?
Both schemes have been extended by five years, until March 2031, as announced by Union Commerce and Industry Minister Piyush Goyal on November 11, 2026.
How much is the total corpus approved for both schemes?
The combined corpus is over ₹9,111 crore — ₹4,111 crore for the Stand-Up India Scheme and ₹5,000 crore for the PMMY Credit Guarantee Fund for Micro Units.
How does a credit guarantee corpus help small businesses get loans?
A credit guarantee corpus does not disburse loans directly. Instead, it covers the risk of default for lenders such as banks, allowing them to extend loans — often collateral-free — to first-time or marginalised borrowers who would otherwise be turned away. This enables a much larger volume of actual lending than the corpus size alone suggests.