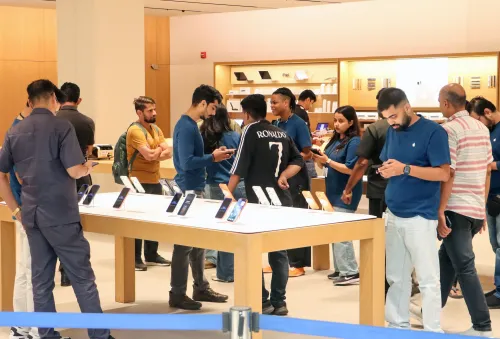
India smartphone shipments fall 20% in Q3 2026, lowest in a decade on memory cost surge
Synopsis
India's smartphone market just posted its worst quarter in ten years — and the festive season offered no rescue. A 20% year-on-year shipment collapse, a 47% crash in the sub-₹20,000 segment, and a full-year forecast of minus 13% paint a picture of an affordability crisis driven by soaring memory component costs that shows no sign of easing before 2027.
Key Takeaways
India's smartphone shipments fell 20 per cent year-on-year in Q3 2026 , the lowest level in a decade, according to Counterpoint Research .
Sub- ₹20,000 smartphone shipments crashed 47 per cent in Q3 2026 as rising prices pushed devices into higher price bands.
OEMs held back on channel inventory even ahead of the festive season, reflecting deep demand uncertainty.
Counterpoint Research forecasts India's smartphone market will shrink by around 13 per cent in full-year 2026 .
Post-festive seasonal slowdown and another expected round of component-driven price hikes add further headwinds.
Growth is projected to shift toward premium and upper-mid segments , with the mass market remaining under structural pressure through 2027 .
India's smartphone shipments declined 20 per cent year-on-year in Q3 2026, hitting their lowest level in a decade as record-high memory component prices drove up device costs and eroded volumes across most brands, according to a report by Counterpoint Research released on Friday, 23 October 2026. The slump signals deepening stress in the world's second-largest smartphone market, with the pain concentrated at the affordable end of the spectrum.
Mass-Market Collapse
The steepest damage was felt in the sub-₹20,000 segment, where shipments plunged 47 per cent in Q3 2026 as rising model prices pushed devices into higher price bands. Research Analyst Shubham Singh of Counterpoint Research noted that 'rising component costs pushed device prices higher, putting increasing pressure on affordability and weakening the traditional mass-market volume engine, particularly below ₹15,000.' Original equipment manufacturers (OEMs) responded by restructuring their portfolios — introducing more 4G and lower-specification models and trading down specifications across select price segments to protect price points while managing margins.
Inventory Caution Even Before Festive Season
In a telling sign of how cautious the industry has become, OEMs held back on channel inventory even heading into the festive season — traditionally the year's strongest demand window. Research Director Tarun Pathak of Counterpoint Research said India's smartphone market is forecast to contract by around 13 per cent in full-year 2026, with sustained pricing pressure bearing down on both affordability and replacement demand. The post-festive seasonal slowdown is expected to compound matters, and elevated component costs are likely to trigger another round of price increases once the festive sale window closes.
Outlook for 2027: Recovery Remains Elusive
The market is expected to remain on a difficult footing through 2027, as higher device prices extend replacement cycles and limit any volume recovery. Growth, according to the Counterpoint Research report, will increasingly migrate toward premium and upper-mid segments, while the mass market stays under pressure from affordability constraints and tighter OEM margins. This structural shift echoes a broader global pattern, where entry-level smartphone volumes have been squeezed by the same memory-cost cycle that has already hit Southeast Asian and Latin American markets.
Financing as the New Conversion Lever
With upfront prices rising, the report flags that no-cost EMIs, exchange offers, and retailer-led promotions 'will become increasingly important conversion levers, helping consumers manage higher upgrade costs.' This points to a model where volume recovery, when it comes, may be driven more by financing innovation than by outright price cuts — a dynamic that benefits large retail chains and telecom operators with bundling capacity over smaller independent retailers.
Point of View
Low-cost devices fuelled by easy consumer credit and aggressive channel expansion; the memory-cost shock has exposed how thin those foundations are. The 47% collapse in the sub-₹20,000 segment is particularly significant: that bracket represents hundreds of millions of first-time and repeat upgraders, and if they are priced out, the replacement cycle elongates in ways that compound year after year. The pivot to no-cost EMIs and exchange offers can paper over the cracks for a season, but it does not solve the underlying affordability equation. Brands that survive this cycle will be those that either absorb margin pressure at the premium end or redesign their mass-market stack around 4G longevity — neither of which is a quick fix.
NationPress
23 Oct 2026
Frequently Asked Questions
Why did India's smartphone shipments fall 20% in Q3 2026?
India's smartphone shipments fell 20 per cent year-on-year in Q3 2026 primarily because record-high memory component prices pushed up device costs, reducing affordability and pulling down volumes across most brands. The decline brought shipments to their lowest level in a decade, according to Counterpoint Research.
Which price segment was hit hardest?
The sub-₹20,000 segment saw the sharpest drop, with shipments declining 47 per cent in Q3 2026 as rising model prices pushed consumers into higher price bands or out of the market entirely. This mass-market segment is considered the traditional volume engine of India's smartphone industry.
What is the full-year 2026 forecast for India's smartphone market?
Counterpoint Research forecasts India's smartphone market will shrink by around 13 per cent in full-year 2026, with sustained pricing pressure continuing to weigh on affordability and replacement demand. Post-festive seasonal slowdown and further component-driven price hikes are expected to add to the strain.
How are smartphone brands responding to the demand slump?
OEMs are restructuring their portfolios by introducing more 4G and lower-specification models, and trading down specifications across some price segments to manage costs while keeping price points stable. They are also holding back on channel inventory rather than building stock ahead of the festive season.
Will India's smartphone market recover in 2027?
Recovery is expected to remain elusive in 2027, as higher device prices continue to extend replacement cycles and limit volume growth, according to Counterpoint Research. Growth opportunities are forecast to shift toward premium and upper-mid segments, while the mass market stays under pressure from affordability constraints.