PHDCCI calls for GST 2.0 reforms to ease compliance, unlock ITC across sectors
Synopsis
India's industry chambers are no longer asking for tweaks — PHDCCI's GST 2.0 blueprint targets the structural nerve of the tax: Section 17(5) ITC restrictions that block credit on factories, warehouses, hotels and runways. If the government acts, it could unlock working capital for infrastructure-heavy businesses and give private capex the push policymakers have long sought.
Key Takeaways
PHDCCI presented a GST 2.0 reform blueprint at a workshop in New Delhi on 18 November 2026 .
The chamber flagged ITC blockages, inverted duty structures and procedural complexity as key pain points across MSMEs, hospitality, aviation, agriculture and infrastructure sectors.
PHDCCI President Anil Gupta called for tax neutrality and seamless ITC flow across the production and services value chain.
A core demand is a review of Section 17(5) of the CGST Act to allow ITC on civil infrastructure, plant and machinery, and capitalised assets used in taxable services.
Specific assets covered include factories, warehouses, cold storage, hotels, airport terminals and runways .
Recommendations are expected to inform pre-Budget consultations ahead of Union Budget 2027 .
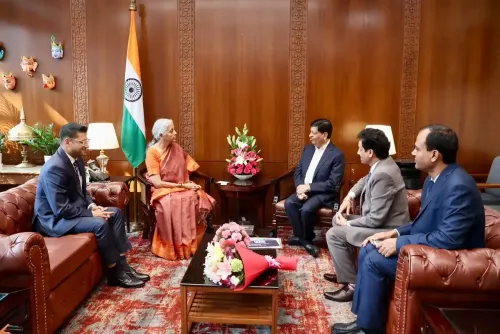
The PHD Chamber of Commerce and Industry (PHDCCI) on 18 November 2026 presented a comprehensive set of recommendations for a proposed GST 2.0 framework, urging the government to reduce compliance burdens, resolve input tax credit (ITC) blockages and improve policy predictability to sharpen India's industrial competitiveness. The proposals were unveiled at the chamber's 'GST 2.0 Workshop: From Compliance Burden to Ease of Doing Business' in New Delhi.
Key Structural Concerns Flagged
PHDCCI identified several persistent fault lines in the current GST architecture that it says continue to hamper businesses. These include restrictions on input tax credit, inverted duty structures, procedural complexities, tax classification disputes and working capital blockages. Sectors calling for relief span MSMEs, food processing, agriculture, hospitality, aviation, infrastructure, energy and export-oriented industries — a breadth that underscores how widely the compliance strain has spread since GST's rollout in 2017.
What PHDCCI President Said
PHDCCI President Anil Gupta argued that the next phase of GST reform must prioritise tax neutrality and seamless credit flow. 'The next phase of GST reforms should focus on strengthening tax neutrality, improving predictability and reducing the compliance burden on businesses,' Gupta said. He added that the objective should be to ensure 'GST operates as a value-added tax system, minimising cascading taxation and allowing eligible input tax credit across the production and services value chain.'
ITC Rationalisation: The Core Demand
The most substantive recommendation concerns a review of Section 17(5) of the Central Goods and Services Tax (CGST) Act, which currently restricts ITC claims on a range of capital expenditures. PHDCCI wants these restrictions lifted for civil infrastructure and capital spending used in providing taxable business services. The proposed relief covers investment in factories, warehouses, cold storage facilities, hotels, airport terminals, runways and other infrastructure assets. The chamber has also sought ITC eligibility for plant and machinery and capitalised assets deployed in taxable business operations, arguing that the present bar inflates production costs and creates avoidable working capital pressure.
Why GST 2.0 Matters Now
India's GST collections have crossed the ₹2 lakh crore mark in multiple months, signalling a maturing revenue base — yet industry groups argue the system still penalises investment-heavy businesses through blocked credits. This is the second major chamber-level push for GST overhaul in as many years, reflecting a growing consensus that the compliance architecture has not kept pace with the revenue success. Notably, the government has itself signalled openness to GST rationalisation, with the GST Council reviewing rate structures and the fitment committee examining several anomalies.
What Happens Next
The PHDCCI recommendations are expected to feed into pre-Budget consultations ahead of the Union Budget 2027. Industry observers say the reform window is narrow: any significant amendment to the CGST Act requires consensus among states through the GST Council, making political alignment as important as technical merit. If adopted, the ITC changes alone could free up substantial working capital for infrastructure-linked businesses and potentially accelerate private capital expenditure — a priority the Centre has repeatedly flagged.
Point of View
The government may keep Section 17(5) intact regardless of industry pressure. The real test of GST 2.0 is whether this round produces a time-bound roadmap or becomes another workshop recommendation that dissolves before the Budget session.
NationPress
18 Nov 2026
Frequently Asked Questions
What is the GST 2.0 framework proposed by PHDCCI?
GST 2.0 is a reform blueprint presented by the PHD Chamber of Commerce and Industry on 18 November 2026, calling for rationalised input tax credit rules, simpler compliance procedures and resolution of inverted duty structures. The framework targets sectors including MSMEs, hospitality, aviation, agriculture and infrastructure.
What is Section 17(5) of the CGST Act and why does PHDCCI want it amended?
Section 17(5) of the Central Goods and Services Tax Act restricts businesses from claiming input tax credit on certain capital expenditures, including civil construction and some plant and machinery. PHDCCI argues these restrictions inflate production costs and block working capital, and wants them reviewed to allow ITC on assets like factories, warehouses, hotels, airport terminals and runways used in taxable business services.
Which sectors are most affected by the current GST compliance burden?
According to PHDCCI, the sectors most affected include MSMEs, food processing, agriculture, hospitality, aviation, infrastructure, energy and export-oriented industries. Each faces some combination of ITC restrictions, inverted duty issues or classification disputes that raise costs.
How could GST 2.0 reforms affect businesses and consumers?
If adopted, ITC rationalisation could free up working capital for investment-heavy businesses, potentially lowering production costs and stimulating private capital expenditure. For consumers, reduced tax cascading in sectors like food processing and hospitality could eventually translate into price relief.
When could GST 2.0 reforms be implemented?
No official timeline has been set. PHDCCI's recommendations are expected to feed into pre-Budget consultations ahead of the Union Budget 2027. Any amendment to the CGST Act requires consensus among states through the GST Council, so implementation depends on both political and technical alignment.