FM Sitharaman hits back at Rahul Gandhi over IDBI Bank ₹53,000 crore stake sale
Synopsis
Finance Minister Nirmala Sitharaman escalated the political battle over IDBI Bank's ₹53,000 crore sale to Canada's Fairfax Financial Holdings, turning Rahul Gandhi's solidarity post into a full-scale indictment of Congress-era 'phonebook banking' — invoking Indira Gandhi, Sanjay Gandhi, Videocon, Kingfisher, and a 1976 SBI episode to argue that the real threat to public sector banks was the party now claiming to protect them.
Key Takeaways
Finance Minister Nirmala Sitharaman on 30 October 2026 defended the IDBI Bank stake sale and accused Congress governments of political interference in public sector bank lending.
On 14 October , the Centre approved sale of a 60.72% stake in IDBI Bank to Canada's Fairfax Financial Holdings for approximately ₹53,000 crore — described as the largest-ever foreign investment in an Indian bank.
Sitharaman alleged that IDBI Bank was forced to lend to groups including Videocon , Winsome , ABG Shipyard , and Kingfisher , which turned into bad loans under Congress -era governments.
The NDA government recapitalised IDBI Bank with more than ₹25,000 crore to revive it, according to Sitharaman.
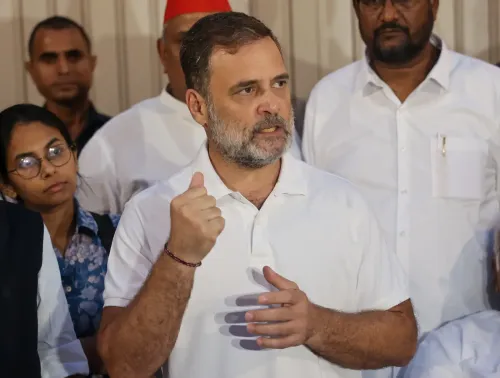
Rahul Gandhi opposed the sale, saying Congress governments built public sector banks while the Modi government was selling them, and expressed solidarity with IDBI Bank employees .
Finance Minister Nirmala Sitharaman on Friday, 30 October 2026, mounted a sharp defence of the Centre's decision to divest a majority stake in IDBI Bank, directly countering criticism from Leader of the Opposition Rahul Gandhi and accusing successive Congress-led governments of using public sector banks as instruments of political patronage, resulting in massive non-performing assets (NPAs).
Sitharaman's Charge Against Congress-Era Banking
Responding to Gandhi's remarks on the proposed stake sale, Sitharaman wrote on X: 'We all know how the Congress has used Banks and financial institutions as personal entities and pressured bank employees to extend loans at their whim, bypassing prudent lending norms.'
The Finance Minister invoked historical precedents, alleging that in 1976, Indira Gandhi's government removed State Bank of India (SBI) Chairman R.K. Talwar after he reportedly refused to yield to political pressure to relax lending conditions for a company linked to Sanjay Gandhi's circle. She further alleged that Sanjay Gandhi had pressured the Central Bank of India over loans to Maruti.
IDBI's Bad Loan Legacy and the NDA's Recapitalisation
Sitharaman alleged that IDBI Bank was inherited by the National Democratic Alliance (NDA) government in poor financial health, having been compelled to lend to large business groups — including Videocon, Winsome, ABG Shipyard, and Kingfisher — with alleged close ties to Congress leaders. These exposures, she stated, subsequently turned into bad loans, inflicting severe losses on the bank.
The Finance Minister said the NDA government led by Prime Minister Narendra Modi revived IDBI Bank through what she described as professionalism, prudence, and a recapitalisation of more than ₹25,000 crore. She added: 'All due process has been followed in the IDBI Bank strategic restructuring, and we have already clarified this yesterday.'
The ₹53,000 Crore Fairfax Deal
On 14 October, the Centre approved the sale of a 60.72% stake in IDBI Bank to Canada's Fairfax Financial Holdings for approximately ₹53,000 crore. According to officials, this would be the largest foreign investment in an Indian bank. The Finance Minister underscored that the bank is now 'poised for its next phase of growth' following the turnaround.
Notably, this transaction follows years of procedural groundwork and regulatory approvals, with the government asserting that all statutory and due-diligence processes have been completed transparently.
Congress-Era 'Phonebook Banking' Allegation
In a pointed formulation, Sitharaman wrote: 'Congress-era banking had a phonebook for the powerful and a rulebook for the common citizens. The era of connection and setting banking is over. Common people now have easy access to loans, and employees are not under pressure to extend loans over the phone calls.'
She also pointed to the White Paper on the Indian Economy released in February 2024, stating it documented further instances of what she characterised as 'blatant scams and economic mismanagement' under previous governments, adding that it 'remains relevant even now.'
Rahul Gandhi's Stand and the Political Fault Line
Gandhi had criticised the sale, arguing that while Congress governments built public sector banks, the Modi administration was selling them. In a post on X, he wrote: 'I stand with the employees of IDBI Bank,' expressing solidarity with staff who fear job security implications of a private foreign takeover.
The exchange marks a sharpening of the political battle lines over disinvestment policy ahead of what analysts expect to be an intensified parliamentary debate. With ₹53,000 crore and India's banking sovereignty at the centre of the dispute, the IDBI sale is unlikely to leave the political agenda anytime soon.
Point of View
But they also risk distracting from present-day scrutiny: whether ₹53,000 crore represents fair value for a bank the taxpayer recapitalised with ₹25,000 crore, and what employment protections will accompany the transfer. Gandhi's 'I stand with IDBI employees' framing is politically astute — it shifts the argument from ideology to livelihoods. The real accountability gap in coverage is the valuation methodology and the post-sale regulatory framework, neither of which has been addressed in either politician's public communication.
NationPress
30 Oct 2026
Frequently Asked Questions
Why is IDBI Bank being sold and who is buying it?
The Centre approved the sale of a 60.72% stake in IDBI Bank to Canada's Fairfax Financial Holdings on 14 October for approximately ₹53,000 crore . The government has described it as the next phase of IDBI Bank's growth after the NDA revived the bank through recapitalisation of more than ₹25,000 crore.
What did Rahul Gandhi say about the IDBI Bank stake sale?
Rahul Gandhi criticised the Centre's decision, arguing that Congress governments had set up public sector banks while the Modi government was selling them. He posted on X expressing solidarity with IDBI Bank employees, citing concerns about job security under foreign private ownership.
What allegations did Nirmala Sitharaman make against the Congress over banking?
Sitharaman alleged that Congress-led governments pressured public sector bank employees to extend loans to politically connected entities, bypassing prudent lending norms. She cited IDBI Bank's exposure to groups like Videocon, Winsome, ABG Shipyard, and Kingfisher — all of which allegedly had Congress connections — as examples of loans that became NPAs.
What is the significance of the Fairfax Financial Holdings deal for India?
The ₹53,000 crore deal is described by officials as the largest foreign investment ever made in an Indian bank. It gives Fairfax Financial Holdings a majority 60.72% stake in IDBI Bank, marking a significant milestone in India's banking disinvestment programme.
What is the White Paper on the Indian Economy that Sitharaman referred to?
The White Paper on the Indian Economy was released by the Finance Ministry in February 2024 , documenting what the government characterised as instances of economic mismanagement and scams under previous administrations. Sitharaman cited it to support her allegations of Congress-era banking malpractice.