ITC Q2 FY27 net profit falls 20% to ₹4,137 crore, margin shrinks to 28%
Synopsis
ITC's Q2 FY27 earnings told a tale of two halves: revenue held up, rising 1.8%, but net profit cratered 20.1% to ₹4,137 crore as margins fell from 34.6% to 28% in a single quarter. With cigarettes still driving the bulk of FMCG revenue, the pressure on the non-cigarette portfolio's profitability is the real story investors need to watch.
Key Takeaways
ITC Limited reported a 20.1% YoY drop in consolidated net profit to ₹4,137 crore in Q2 FY27 .
Consolidated revenue from operations rose a modest 1.8% to ₹18,401 crore .
Operating margin contracted sharply to 28% from 34.6% in the preceding quarter.
FMCG segment revenue reached ₹22,503.30 crore ; cigarettes contributed ₹15,536.13 crore .
Agri business revenue grew to ₹4,451.69 crore ; paperboards and packaging rose to ₹3,015.85 crore .
ITC shares closed at ₹266.40 on 2 November , up 0.30% , after touching an intra-day high of ₹269.30 .
Diversified conglomerate ITC Limited on Monday, 2 November 2026 reported a 20.1% year-on-year decline in consolidated net profit for the second quarter of FY27 (July–September 2026), according to its stock exchange filing. Consolidated net profit came in at ₹4,137 crore, down sharply from ₹5,176 crore posted in Q2 FY26.
Revenue Growth Masks Profitability Pressure
Consolidated revenue from operations edged up 1.8% to ₹18,401 crore in Q2 FY27, compared with ₹18,081 crore a year earlier. However, the modest top-line growth was overshadowed by a significant margin contraction — operating margins narrowed to 28% from 34.6% in the preceding quarter, according to the regulatory filing. Total segment results also declined to ₹5,156.55 crore from ₹6,320.72 crore in the year-ago period.
FMCG Leads Revenue, Cigarettes Dominate the Segment
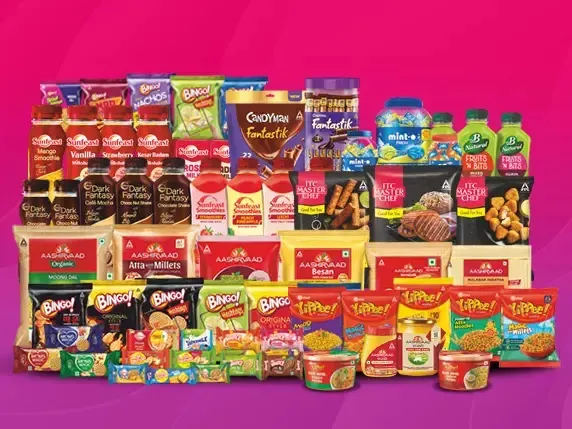
Within ITC's standalone operations, the FMCG segment remained the largest revenue contributor. Segment revenue surged to ₹22,503.30 crore in Q2 FY27 from ₹14,746.35 crore in the corresponding period of FY26 — a sharp jump attributed to standalone business consolidation. The cigarettes business contributed ₹15,536.13 crore in revenue, while the non-cigarette FMCG portfolio generated ₹6,967.17 crore.
Agri and Paperboards Post Sequential Gains
The agri business segment recorded growth, with revenue rising to ₹4,451.69 crore from ₹3,976.24 crore in Q2 FY26. Revenue from the paperboards, paper and packaging business also improved, climbing to ₹3,015.85 crore from ₹2,219.92 crore in the year-ago quarter. The company's standalone business delivered growth across major segments, the filing noted.
Stock Reaction and Market Context
ITC shares ended marginally higher on the day of the results, closing at ₹266.40 on 2 November — up 0.30%, or ₹0.80, from the previous close of ₹265.60. During the session, the stock touched an intra-day high of ₹269.30 and a low of ₹264.00. The muted share price reaction suggests markets had partially priced in the earnings weakness ahead of the announcement.
What to Watch Next
The scale of margin compression — a 660 basis point decline quarter-on-quarter — will be closely scrutinised by analysts assessing whether the pressure is seasonal or structural. ITC's ability to restore profitability in Q3 FY27, particularly as input costs and competitive intensity in non-cigarette FMCG remain elevated, will be the key metric for investors in the quarters ahead.
Point of View
But with non-cigarette FMCG revenue still lagging in profitability, ITC's much-touted diversification story is yet to fully materialise on the bottom line. If margin pressure persists into Q3, questions about ITC's demerger-driven restructuring and capital allocation will return to the fore.
NationPress
2 Nov 2026
Frequently Asked Questions
What was ITC's net profit in Q2 FY27?
ITC reported a consolidated net profit of ₹4,137 crore in Q2 FY27 (July–September 2026), a decline of 20.1% compared to ₹5,176 crore in Q2 FY26.
Why did ITC's profit fall so sharply in Q2 FY27?
The profit decline was driven by a significant contraction in operating margins, which fell to 28% from 34.6% in the preceding quarter. Total segment results also dropped to ₹5,156.55 crore from ₹6,320.72 crore in the year-ago period, indicating broad-based profitability pressure.
How did ITC's FMCG and cigarettes business perform in Q2 FY27?
The FMCG segment was the largest revenue contributor, with segment revenue rising to ₹22,503.30 crore. Within FMCG, the cigarettes business contributed ₹15,536.13 crore in revenue, while the non-cigarette FMCG portfolio generated ₹6,967.17 crore.
How did ITC shares react to the Q2 earnings?
ITC shares closed marginally higher at ₹266.40 on 2 November, up 0.30% from the previous close of ₹265.60. The stock hit an intra-day high of ₹269.30 and a low of ₹264.00, suggesting markets had partially anticipated the weaker results.
Did ITC's other business segments grow in Q2 FY27?
Yes, the agri business revenue rose to ₹4,451.69 crore from ₹3,976.24 crore a year earlier, and paperboards, paper and packaging revenue grew to ₹3,015.85 crore from ₹2,219.92 crore in Q2 FY26.