China housing rebound hollow: Resales top 50%, new construction keeps falling
Synopsis
China's housing rebound is a statistical mirage. Resale transactions now account for over half of all home sales — up from 27% in 2020 — but ownership transfers do not build GDP. With property investment set to fall nearly 20% this year and the failed presale model still spooking buyers away from new homes, the recovery narrative being pushed by officials looks increasingly hollow.
Key Takeaways
Second-hand home transactions in China have surged from 27% in 2020 to over 50% in 2026 , making resales the dominant market activity.
Resale transactions contribute little to GDP beyond services like brokerage fees — they are ownership transfers, not new production.
Property investment is projected to contract by nearly 20% in 2026 , deepening fiscal strain on local governments.
China's presale housing model has been flagged as a structural market failure, turning buyers into unwilling creditors of developers.
Officials framing the resale surge as a 'new phase' are pushing a 'hollow narrative,' according to the report, as oversupply and construction weakness remain unaddressed.
China's housing market, widely described as stabilising in recent months, is masking a deeper structural problem: the apparent recovery is driven almost entirely by resale transactions rather than fresh construction, leaving the country's broader economic strains largely unresolved, according to a new report.
Resales Dominate, But Add Little to GDP
The share of second-hand home transactions in China has surged from roughly 27 per cent in 2020 to over 50 per cent in 2026, according to the report. While this uptick has provided some relief to market activity, analysts note it is fundamentally an ownership transfer — not new production. Beyond ancillary services such as brokerage fees, resale activity contributes little to gross domestic product (GDP).
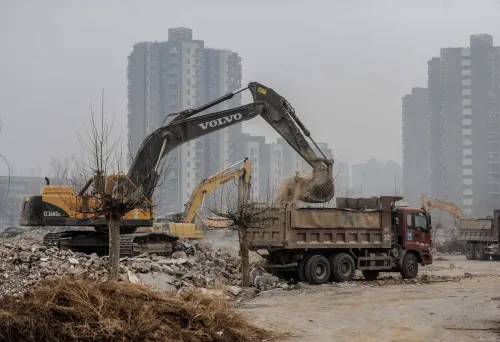
By contrast, new residential construction, which is a significant direct contributor to GDP, continues to contract. The report states that property investment is expected to shrink by nearly 20 per cent this year alone, compounding fiscal pressures on local governments already starved of land-sale revenues.
Decades of Growth Model Now Unwinding
'As the economy for decades was fuelled by land sales, construction projects, employment, and demand for basic industry goods like steel and cement, it has seen a slow and steady downturn. This downturn further impedes GDP growth,' the report observed.
For years, China's growth engine ran on a property-led model: municipalities sold land to developers, developers pre-sold homes to buyers, and proceeds funded everything from local infrastructure to social services. That model is now visibly fraying, with consequences rippling through steel, cement, and construction employment.
The 'Presale' Model: A Structural Failure
The report singles out China's presale housing model — under which buyers pay for homes years before completion — as a textbook example of market failure. 'With money locked in for a long period, home buyers found themselves as unwilling creditors to the building companies,' the report noted.
This adverse experience, amplified by high-profile developer collapses in recent years, has pushed buyers decisively toward existing homes and away from off-plan purchases. The result: a reinforcing cycle where fresh housing investment continues to slump even as resale volumes recover.
Why the 'New Phase' Framing Does Not Hold
Chinese officials have sought to frame the resale surge as evidence that the market has entered a new, healthier phase. The report pushes back sharply, calling this a 'hollow narrative.' Second-hand sales stabilise turnover on paper, but they do not address the country's significant oversupply of unsold new homes, nor do they restore the construction-related employment and output that drove China's prior growth trajectory.
Notably, this divergence between official framing and underlying data is not new — Beijing has repeatedly signalled housing stabilisation since late 2023, yet new construction starts have continued to decline in most quarters since then.
What to Watch
Markets and policymakers will be watching whether Beijing rolls out fresh demand-side stimulus — including mortgage rate cuts or additional loosening of purchase restrictions in tier-one cities — to reverse the investment slide. Without a genuine recovery in new construction, the drag on China's GDP growth, and by extension on global commodity demand including India's steel and iron ore exports, is likely to persist well into 2027.
Point of View
Including India, have priced in a Chinese construction recovery that may simply not arrive. The presale model critique is also overdue — it was always a Ponzi-adjacent structure that transferred developer risk onto ordinary households, and its unravelling now leaves policymakers with no clean exit.
NationPress
12 Oct 2026
Frequently Asked Questions
Why is China's housing recovery described as hollow?
The recovery is driven almost entirely by resale transactions, which are ownership transfers and contribute little to GDP, rather than by new construction, which directly boosts economic output. Property investment is still expected to shrink by nearly 20% in 2026, leaving the underlying economic weakness intact.
How much have second-hand home sales risen in China?
The share of second-hand home transactions has climbed from roughly 27% in 2020 to over 50% in 2026, according to the report. While this has provided some relief to market turnover, it does not address oversupply or stimulate new construction activity.
What was wrong with China's presale housing model?
Under the presale model, buyers paid for homes years before completion, effectively becoming involuntary creditors to developers. When several major developers collapsed, buyers were left exposed, pushing them toward existing homes and away from new off-plan purchases — deepening the slump in fresh housing investment.
How does the housing slump affect China's economy?
For decades, China's growth was anchored in land sales, construction, and demand for materials like steel and cement. The continued fall in new residential construction is dragging down GDP growth, reducing local government revenues, and creating knock-on effects in construction-linked industries and employment.
What would a genuine housing recovery in China require?
A real recovery would need a sustained rebound in new construction starts, absorption of the significant stock of unsold homes, and restoration of buyer confidence in off-plan purchases — none of which resale activity alone can deliver. Analysts are watching for further demand-side stimulus such as mortgage rate cuts or eased purchase restrictions in major cities.