India Grade A warehousing absorption hits 54 mn sq ft in Jan-Sep 2026
Synopsis
India's Grade A warehousing sector absorbed 54 million sq. ft. in just nine months — outstripping fresh supply by nearly 7 million sq. ft. Even with demand down 18% year-on-year, occupiers are gobbling up institutional logistics space faster than developers can build it, and rents in Mumbai's Bhiwandi are surging at nearly 12% annually.
Key Takeaways
India's Grade A and A+ warehousing sector absorbed 54 million sq. ft. in January–September 2026 , exceeding new supply of 47.1 million sq. ft.
Demand moderated 18 per cent year-on-year ; new supply declined around 3 per cent over the same period.
Total Grade A ready stock stood at 492.7 million sq. ft. at end- Q3 CY26 , projected to reach 510 million sq. ft. by end-2026.
Pan-India vacancy was 10.5 per cent , down 80 basis points year-on-year; market rent averaged ₹28.6 per sq. ft. per month.
Pune ( 11.5 mn sq. ft. ) and MMR ( 10.6 mn sq. ft. ) together made up 41 per cent of national demand.
Manufacturing (31%), 3PL (19%), and automotive (16%) collectively drove 66 per cent of Q3 absorption.
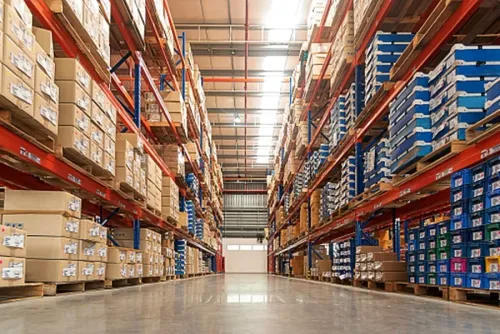
India's Grade A and A+ warehousing sector absorbed 54 million sq. ft. in the first nine months of calendar year 2026, outpacing new supply additions of 47.1 million sq. ft. in the same period, according to a joint report released on 20 November 2026 by CREDAI and CRE Matrix. The demand-supply gap underscores robust occupier appetite for institutional-grade logistics space even as absorption moderated on a year-on-year basis.
Demand and Supply Dynamics
Warehousing demand eased nearly 18 per cent year-on-year during January–September 2026, while new supply also contracted, falling around 3 per cent over the same period. Despite the moderation, absorption still exceeded new completions by roughly 6.9 million sq. ft., keeping the market in a net-positive absorption position for the year so far.
India's total Grade A and A+ ready stock stood at 492.7 million sq. ft. at the end of Q3 CY26 and is projected to reach approximately 510 million sq. ft. by year-end, the report forecasted.
Vacancy and Rental Trends
The pan-India vacancy level stood at 10.5 per cent at the close of Q3 2026 — 80 basis points lower than a year earlier, though it edged up 20 basis points sequentially, suggesting some near-term pockets of oversupply in select micro-markets. Market rent averaged ₹28.6 per sq. ft. per month, while passing rents rose 3 per cent year-on-year to ₹27.3 per sq. ft. per month, indicating steady landlord pricing power.
Pune and MMR Lead Absorption
Pune topped the seven markets tracked, recording 11.5 million sq. ft. of absorption, followed closely by the Mumbai Metropolitan Region (MMR) at 10.6 million sq. ft. Together, the two markets accounted for approximately 41 per cent of national warehousing demand during the period.
Pune added 9.3 million sq. ft. of new supply and registered a vacancy rate of 8.4 per cent. MMR's vacancy stood at 8.3 per cent, while quarterly market rents in the region surged 11.8 per cent year-on-year — the sharpest rental appreciation among the markets covered. Within MMR, Bhiwandi alone accounted for 74 per cent of the city's quarterly demand, reinforcing its status as the country's foremost logistics hub.
Sector-wise Demand Drivers
Manufacturing was the largest demand driver, representing 31 per cent of national Q3 CY26 absorption. Third-party logistics (3PL) followed at 19 per cent, and automotive contributed 16 per cent. Collectively, these three sectors drove 66 per cent of quarterly demand, underlining the central role of industrial production and organised supply chains in India's Grade A warehousing market.
Industry Outlook
Abhishek Kiran Gupta, CEO and Co-founder of CRE Matrix, said: 'With Grade A warehousing stock projected to reach 510 million sq. ft. by the end of 2026, the sector's long-term growth trajectory remains supported by industrial expansion, evolving supply chains and demand for institutional-grade logistics infrastructure.'
Analysts note that the structural tailwinds — including India's push to integrate global supply chains, the growth of e-commerce, and the formalisation of logistics under the GST regime — are expected to sustain Grade A demand into 2027 and beyond.
Point of View
Not unravelling. The real story is concentration risk: Pune and MMR together account for 41 per cent of national absorption, meaning India's warehousing boom remains geographically lopsided. Bhiwandi's 74 per cent share of MMR demand points to infrastructure bottlenecks that could cap rent growth if road and rail connectivity does not keep pace. The sector's structural story — GST formalisation, e-commerce, China-plus-one supply-chain shifts — remains intact, but the moderation is a reminder that even a good thesis has cycles.
NationPress
20 Nov 2026
Frequently Asked Questions
How much Grade A warehousing was absorbed in India in January–September 2026?
India's Grade A and A+ warehousing sector absorbed 54 million sq. ft. during January–September 2026, according to a CREDAI and CRE Matrix report released on 20 November 2026. This exceeded new supply additions of 47.1 million sq. ft. in the same period.
Which cities led India's warehousing demand in 2026?
Pune led with 11.5 million sq. ft. of absorption, followed by the Mumbai Metropolitan Region (MMR) at 10.6 million sq. ft. Together they accounted for approximately 41 per cent of India's warehousing demand in January–September 2026.
What is the current vacancy rate in India's Grade A warehousing market?
The pan-India vacancy rate stood at 10.5 per cent at the end of Q3 CY26, which is 80 basis points lower than a year earlier, though it rose 20 basis points from the previous quarter. Market rent averaged ₹28.6 per sq. ft. per month.
Which sectors are driving warehousing demand in India?
Manufacturing accounted for 31 per cent of national Q3 CY26 warehousing absorption, followed by third-party logistics (3PL) at 19 per cent and automotive at 16 per cent. These three sectors collectively drove 66 per cent of quarterly demand.
What is the outlook for India's Grade A warehousing stock by end-2026?
India's Grade A and A+ warehousing stock is projected to reach approximately 510 million sq. ft. by the end of 2026, up from 492.7 million sq. ft. at the close of Q3. CRE Matrix's CEO cited industrial expansion and evolving supply chains as the key long-term growth drivers.