Tamil Nadu hikes gold loan limit to ₹10,000/gram after newborn ring scheme launch
Synopsis
Tamil Nadu has raised the cooperative gold loan ceiling from ₹7,000 to ₹10,000 per gram — a direct policy follow-through to its newborn gold ring scheme that could push 441 kg of gold annually into households. With cooperative rates still below private lenders, the state is making a calculated push to pull low-income borrowers away from pawnbrokers and into formal credit.
Key Takeaways
Tamil Nadu has raised the cooperative bank gold loan ceiling from ₹7,000 to ₹10,000 per gram .
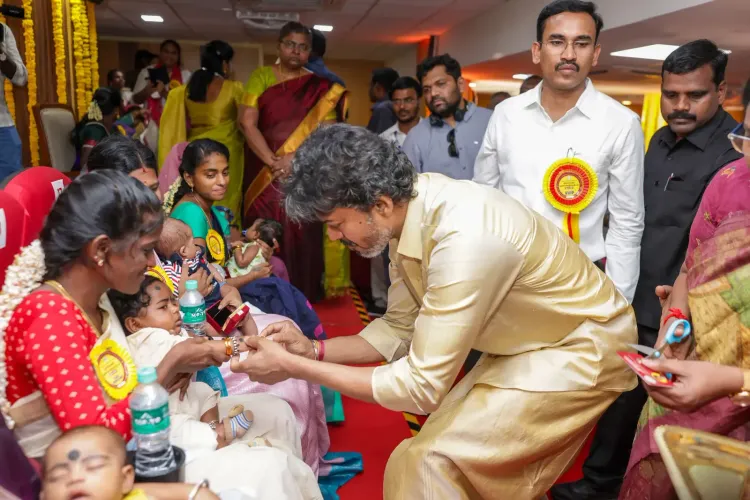
The revision follows the launch of the Thaai Maaman Thanga Mothiram Thittam , which provides a one-gram, 22-carat gold ring to newborns at government hospitals.
Government hospitals record about 4.4 lakh deliveries annually, potentially adding 441 kg of gold to households each year.
Gold was priced at ₹13,675 per gram on Monday; cooperative interest rates remain at 13 per cent , lower than most private lenders.
PACCS profit margins have been capped at 2.25 per cent , and their cash-credit-funded gold loans must carry rates 1.25 percentage points below branch-direct rates.
Tamil Nadu's Cooperation Department has raised the gold loan ceiling at cooperative banks and societies from ₹7,000 to ₹10,000 per gram, a move aimed at expanding institutional credit access for economically weaker borrowers and reducing dependence on private moneylenders. The revision, announced in Chennai, comes roughly a week after the state launched the Thaai Maaman Thanga Mothiram Thittam — a scheme that gifts a one-gram, 22-carat gold ring to newborns delivered at government health facilities.
Background: The Newborn Ring Scheme
The Thaai Maaman Thanga Mothiram Thittam, launched in late September, positions the state government as a direct participant in gold distribution at the grassroots level. With government hospitals recording an annual average of approximately 4.4 lakh deliveries, the scheme could channel around 441 kg of gold into the market each year. The gold loan limit revision is widely seen as a complementary policy step — if families receive gold, institutions must be ready to lend meaningfully against it.
The Old Rule and What Has Changed
Previously, cooperative banks and societies extended loans equivalent to 75 per cent of the value of pledged jewellery, capped at a maximum of ₹7,000 per gram. For loans repayable within six months, lending was permitted up to 75 per cent of the monthly average gold value without a per-gram ceiling. The revised ceiling of ₹10,000 per gram brings cooperative lenders significantly closer to what the broader market offers.
Where Cooperatives Now Stand Against Other Lenders
With gold priced at ₹13,675 per gram on Monday, the competitive landscape for gold lending is as follows: private commercial banks offer roughly ₹9,600 to ₹10,400 per gram; public sector banks lend approximately ₹8,800 to ₹9,300 per gram; and private pawnbrokers, loan-focused non-banking financial companies, and trading companies offer around ₹10,500 to ₹11,000 per gram. Bank interest rates range from 14 to 18 per cent. The Cooperation Department raised its gold loan interest rate from 12 to 13 per cent last year, meaning cooperative borrowers still access credit at a lower rate than most alternatives despite the ceiling hike.
Decisions on Cooperative Credit Societies
A separate meeting at the office of the Registrar of Cooperative Societies produced two additional decisions. First, the profit margin of Primary Agricultural Cooperative Credit Societies (PACCS) was capped at 2.25 per cent. Second, PACCS gold loans funded through cash credit from central cooperative banks must carry an interest rate 1.25 percentage points below the rate charged on gold loans issued directly by branches of those banks — a structural concession intended to make credit routed through agricultural cooperatives cheaper for end borrowers.
Why This Matters for Borrowers
Officials stated that the enhanced ceiling would encourage more customers to approach cooperative banks, where the interest rate remains lower than at private lenders and pawnbrokers. Notably, the changes collectively address both the quantum of credit available against pledged jewellery and the pricing architecture of loans flowing through agricultural cooperative societies — a two-pronged attempt to deepen financial inclusion in the state. With gold prices at elevated levels and a new supply of government-issued gold rings entering households, the policy alignment is deliberate.
Point of View
Then ensure cooperative lenders can offer a competitive amount against that same gold. But the arithmetic matters — at ₹10,000 per gram against a market price of ₹13,675, cooperatives still offer a lower loan-to-value than pawnbrokers at ₹10,500-₹11,000. The real competitive advantage remains the interest rate, which at 13 per cent undercuts private NBFCs and pawnbrokers by several points. Whether that margin is enough to shift deeply entrenched borrowing habits away from informal lenders is the open question. The PACCS margin cap is a meaningful consumer protection measure, but enforcement capacity across hundreds of agricultural societies will determine its real-world impact.
NationPress
6 Oct 2026
Frequently Asked Questions
Why has Tamil Nadu increased the gold loan limit at cooperative banks?
Tamil Nadu raised the per-gram gold loan ceiling from ₹7,000 to ₹10,000 at cooperative banks and societies to make institutional credit more accessible to economically weaker borrowers and reduce their reliance on private moneylenders and pawnbrokers. The move complements the state's recently launched newborn gold ring scheme.
What is the Thaai Maaman Thanga Mothiram Thittam scheme?
The Thaai Maaman Thanga Mothiram Thittam is a Tamil Nadu government scheme that provides a one-gram, 22-carat gold ring to newborns delivered at government health facilities. With around 4.4 lakh annual deliveries at government hospitals, it could introduce approximately 441 kg of gold into households each year.
How do cooperative bank gold loan rates compare with private lenders?
With gold at ₹13,675 per gram, cooperative banks now lend up to ₹10,000 per gram at 13 per cent interest. Private commercial banks offer ₹9,600–₹10,400 at 14–18 per cent, while pawnbrokers and NBFCs offer ₹10,500–₹11,000 at typically higher rates. Cooperatives remain the cheapest formal option, though not the highest-lending one.
What decisions were taken regarding Primary Agricultural Cooperative Credit Societies (PACCS)?
A meeting at the Registrar of Cooperative Societies capped PACCS profit margins at 2.25 per cent. It also stipulated that PACCS gold loans funded via cash credit from central cooperative banks must carry an interest rate 1.25 percentage points below the rate on gold loans issued directly by those banks' branches.
Who benefits most from the revised gold loan ceiling in Tamil Nadu?
Economically weaker borrowers who rely on pledged jewellery for short-term credit stand to benefit most, as they can now access a larger loan amount from cooperative institutions without approaching higher-cost private pawnbrokers or NBFCs. Families receiving gold rings under the newborn scheme are a direct target demographic of the new policy.